

Blogs
Dental Market 2026: Why 9.25% CAGR and US$68.49 Billion Forecast Reshape Strategy
By PW Consulting, 2026-09-21
Navigating the Dental Market: Strategic Trends and Commercial Opportunities in a High-Growth Landscape
The global dental industry is entering a phase of accelerated expansion, reshaping how manufacturers, distributors, and clinical providers approach long-term strategy. With the market reaching approximately 36.9 billion USD in 2025 and projected to climb steadily toward 68.49 billion USD by 2032, the sector is delivering a compound annual growth rate of 9.25 percent. This trajectory reflects more than incremental demand; it signals a structural transformation driven by technology adoption, evolving practice models, and shifting consumer expectations. For executives and investors operating in this space, the question is no longer whether the market will grow, but how to position portfolios, operations, and partnerships to capture value while navigating operational friction.
Behind the headline figures lies a market defined by uneven growth, regional disparity, and intensifying competition. Concentration metrics show that the top three players command roughly 42.8 percent of industry revenue, while the top five control approximately 48.2 percent. This level of consolidation indicates a landscape where scale, brand trust, and integrated product ecosystems confer meaningful advantages, yet it also leaves room for specialized innovators and regional disruptors to carve out defensible niches. Understanding where growth is concentrating and where pressure is mounting requires looking past aggregate numbers and examining the forces actively reshaping competitive dynamics.
Market Size, Growth Trajectory, and the Cost Reality
The dental market has expanded consistently from a base of 25.87 billion USD in 2020 to an estimated 36.9 billion USD in 2025, with the forecast horizon extending through 2032. Growth is not linear. Early pandemic-era disruptions gave way to a rebound that accelerated procedure volumes, supply chain normalization, and digital integration. By 2024, the market had surpassed 34.7 billion USD, and the momentum continues into the mid-to-late 2020s, with projections reaching 41.45 billion USD in 2026 and climbing toward 57.55 billion USD by 2030 before approaching 68.49 billion USD at the end of the forecast period.
Dental Material Market
This expansion is occurring alongside a tangible cost squeeze. Prices for dental equipment and supplies have risen by 5 percent from the beginning of 2025, placing additional pressure on practice margins and procurement budgets. At the same time, provider reimbursement rates remained stable in September 2025 but have not kept pace with broader inflation and practice expense growth. The result is a market where top-line demand is strong, but profitability depends increasingly on operational efficiency, pricing discipline, and the ability to differentiate through higher-value solutions rather than volume alone.
Key Challenges and Inflection Points
Three interconnected challenges are redefining strategic priorities across the dental sector.
- Margin compression amid rising input costs: Supply price increases and labor cost dynamics are testing the economics of both manufacturers and clinical practices. Dental office employment declined marginally by 0.2 percent in December 2025 compared with the prior month, even as annual employment rose 1.3 percent, suggesting a market that is adding roles over time but remains sensitive to month-to-month cost fluctuations. Practices and suppliers alike must find ways to improve throughput, reduce waste, and justify price adjustments without eroding loyalty.
- Reimbursement gaps and demand sustainability: Stable reimbursement is not equivalent to sufficient reimbursement. When payment structures lag inflation and operational expenses, providers face pressure to manage case acceptance, optimize scheduling, and prioritize treatments with stronger economic returns. This environment favors companies that can demonstrate measurable clinical efficiency, reduced chair time, or long-term cost savings.
- Regulatory clarity and ethical expectations: Industry standards are becoming more explicit. In May 2025, the Dental Trade Alliance issued a revised U.S. Code of Ethics that provides greater clarity on interactions between manufacturers, distributors, and professionals. For businesses, this creates both a compliance requirement and a trust opportunity. Firms that proactively align with transparent engagement standards can strengthen reputational capital while reducing legal and commercial risk.
Key Drivers Shaping the Dental Market
Growth in the dental sector is not accidental. It is being propelled by a combination of technological breakthroughs, evolving consumer behavior, practice consolidation, and structural shifts in supply chains and cost bases. Each driver reinforces the others, creating a market where incremental improvements are increasingly insufficient and integrated solutions gain advantage.
PW Consulting Automotive & Machinery Research Center
Technology Innovation and Digital Workflow Acceleration
Digital dentistry continues to be one of the most powerful catalysts for change. From intraoral scanning and computer-aided design and manufacturing workflows to clear aligner ecosystems and advanced restorative materials, technology is compressing treatment timelines and expanding the scope of what can be delivered efficiently in-office. Product launches throughout 2025 illustrate the pace of innovation. In March 2025, COLTENE Group introduced six new innovations at IDS 2025, including HySolate Liquid Dam for advanced gingiva protection and Kenda ShapeGuard for next-generation polishing. These additions reflect a broader industry focus on precision, protection, and streamlined clinical steps.
In the same month, Parkell introduced HyperFIL+ Bulk-Fill Composite, TurboSensor+360 Ultrasonic Scaler, and DuraTip Ultrasonic Insert, signaling continued investment in materials and instrumentation designed to improve procedural speed and outcome consistency. By July 2025, Kerr Dental expanded its offerings with Next-Generation elements Connect and Apex Connect shaping solutions, SimpliCut Pre-Sterilized Diamond Burs, ZenSeal Bioceramic Sealer, and ZenFlex ONE Reciprocating File. Garrison Dental Solutions followed with Composi-Tight 3D Fusion Full Curve Matrix Bands for Class II composite restorations. Collectively, these launches demonstrate a market moving toward specialization, biocompatibility, and workflow integration rather than commoditized replacement parts.
For commercial strategy, the implication is clear. Innovation cycles are shortening, and differentiation increasingly depends on how well a product fits into a digital or clinical workflow rather than on isolated feature claims. Companies that provide compatible, evidence-supported, and easy-to-adopt solutions are better positioned to capture repeat usage and reduce switching friction.
Policy, Regulation, and Ethical Commercial Standards
The regulatory environment is becoming more structured, with implications for how companies engage with dental professionals and how distributors manage commercial relationships. The May 2025 revision of the U.S. Code of Ethics by the Dental Trade Alliance is a meaningful example. By increasing clarity around interactions among manufacturers, distributors, and practitioners, the update raises the bar for transparency and consistent conduct.
This matters for market dynamics because trust and compliance are increasingly intertwined with purchasing decisions. In a concentrated market where long-term relationships matter, ethical clarity can become a competitive differentiator. It also reduces ambiguity for procurement teams evaluating vendor partnerships. For manufacturers and distributors, proactive alignment with evolving standards is no longer a back-office compliance task; it is part of the commercial narrative and risk management framework.
Demand-Side Shifts and Practice Model Evolution
On the demand side, patient expectations and practice structures are changing simultaneously. Consumers are increasingly informed about aesthetic options, preventive care, and minimally invasive treatments, which influences case mix and treatment planning. At the same time, practice delivery models continue to evolve. Group practices and consolidated entities are gaining share relative to solo practices, altering purchasing patterns, volume commitments, and the value proposition of centralized supply chains.
This shift affects product strategy in two ways. First, larger practice groups often prioritize standardization, service reliability, and total cost of ownership across multiple locations. Second, solo and smaller practices may value flexibility, rapid turnaround, and solutions that reduce reliance on specialized labor. Companies that can tailor engagement models to these differing needs, while maintaining consistent product quality, are more likely to sustain growth across customer segments.
Supply Chain Pressures and Cost Structure Realignment
Supply chain and cost dynamics are reshaping margins and procurement behavior. The 5 percent increase in equipment and supply prices since early 2025 is a concrete indicator of continued inflation pressure within the sector. Combined with reimbursement that has not matched overall inflation and practice expenses, the environment rewards efficiency and penalizes waste.
This is not solely a cost problem; it is a strategic one. Manufacturers and distributors that can stabilize pricing, improve inventory predictability, and reduce lead-time variability create tangible value for buyers. Likewise, clinical providers that invest in durable, multi-use, or workflow-enhancing tools can offset some of the cost pressure through productivity gains. In this context, the supply chain is becoming a source of competitive advantage rather than a passive cost center.
Competitive Landscape and Leading Strategies
The dental market is defined by a mix of global manufacturers, specialized material and equipment producers, and large-scale distributors. The presence of well-established players across multiple categories creates a competitive environment where scale, portfolio breadth, and innovation cadence all matter.
Strategic Positioning of Key Players
Dentsply Sirona Inc., headquartered in Charlotte, North Carolina, operates as a leading global manufacturer spanning dental equipment, implants, restorative materials, and digital solutions. Its broad portfolio allows the company to address multiple stages of the clinical workflow, which supports cross-selling opportunities and integrated solution selling. In August 2025, the company launched a new implant product selection guide on its U.S. e-commerce platform alongside the DS OmniTaper Implant, an example of using digital channels to simplify product navigation and support clinician decision-making.
The Straumann Group, based in Basel, Switzerland, is a global leader in dental implants, prosthetics, and regenerative products. Its focus on high-value implant and regenerative solutions positions it around long-term clinical outcomes and specialized customer education. Align Technology, Inc., located in San Jose, California, has built its identity around Invisalign clear aligners and digital orthodontics technology, illustrating how a focused innovation platform can reshape a subcategory and drive patient demand.
Ivoclar Vivadent AG, headquartered in Schaan, Liechtenstein, concentrates on dental materials, ceramics, and restorative products, where reputation for material performance and clinical reliability matters greatly. GC Corporation, based in Tokyo, Japan, provides dental materials and equipment for restorative and preventive applications, reflecting a strong foothold in material science and practitioner support. COLTENE Group, with headquarters in Altstätten, Switzerland, manufactures dental consumables, endodontics, and restorative solutions, and its March 2025 launch activity underscores continued push in product diversification.
Other notable participants reinforce the breadth of the market. Kerr Corporation, based in Orange, California, supplies dental materials and rotary instruments for restorative and endodontic procedures. 3M Oral Care, in St. Paul, Minnesota, provides oral care materials and preventive dental products. Henry Schein, Inc., Melville, New York, and Patterson Companies, Inc., St. Paul, Minnesota, operate as major full-service distributors offering supplies, equipment, and technology solutions. Benco Dental Supply Company, Pittston, Pennsylvania, serves more than 30,000 professionals across the United States through a multi-location distribution model. Yankee Dental Congress, Southborough, Massachusetts, functions as a trade association and supplier network supporting dental professionals and commercial activity.
Evolving Market Structure: Consolidation, Specialization, and New Entrants
The competitive map is evolving along multiple axes. On one hand, concentration levels indicate that larger players continue to capture meaningful share through portfolio depth, brand familiarity, and distribution reach. On the other hand, the steady stream of targeted product launches suggests that differentiation remains possible through niche performance, material innovation, and workflow fit. This creates a dual dynamic: scale advantages are real, but they do not automatically neutralize specialized competitors who solve specific clinical pain points better than broader offerings.
Distributors also play a critical role in shaping the market. Full-service distributors can aggregate demand, simplify procurement, and provide localized support, which is especially valuable as practices seek to manage complexity and cost. At the same time, e-commerce platforms and digital product guides are changing how clinicians compare and select items, reducing friction in the purchasing journey and increasing the importance of clear product information and evidence-supported positioning.
New entrants and smaller innovators are likely to persist where they can bring a distinct technical advantage, a more agile go-to-market model, or a compelling cost-performance balance. The challenge for incumbents is to maintain innovation velocity and customer responsiveness, while the challenge for newer players is to scale trust, service, and distribution without eroding their differentiation.
Forward Outlook: Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends appear likely to shape where value is created and where risk accumulates. These trends are not isolated predictions; they are extensions of current economics, product activity, and regulatory direction.
Trend 1: Digital and Material Innovation Will Continue to Redefine Workflow Value
The trajectory of 2025 product launches points toward continued refinement in materials, instrumentation, and workflow compatibility. Bulk-fill composites, bioceramic sealers, advanced polishing and protection products, and improved shaping and matrix systems all suggest a market that is optimizing for speed, precision, and clinical predictability. Over the forecast period, this should reinforce demand for solutions that help providers complete more cases with fewer steps and better consistency.
The commercial opportunity lies in bundling compatibility and support with product performance. Manufacturers that can demonstrate how their offerings integrate into scanning, milling, sterilization, and restoration workflows may gain stronger stickiness and justify premium positioning. The risk is that rapid innovation raises customer expectations and shortens product life cycles, requiring continuous investment in research, clinical validation, and education.
Trend 2: Cost Pressure Will Accelerate Efficiency-Based Competition
Because supply prices have risen and reimbursement has not fully matched inflation and practice expenses, efficiency will remain a central battleground. Practices will continue to evaluate tools and consumables not only by clinical outcome but also by throughput, training burden, and replacement frequency. Distributors and manufacturers that can offer predictable pricing, reliable availability, and products that reduce procedure time will have a stronger value proposition.
For investors and executives, this trend suggests that profitability may increasingly depend on operational excellence and portfolio mix rather than on market growth alone. Companies with higher exposure to cost-sensitive consumables may face more pressure, while those offering higher-value equipment or differentiated materials may have more room to defend margins. The uncertainty lies in how long cost pressures persist and whether reimbursement structures adapt in response.
Trend 3: Consolidated Practices and Transparent Commercial Standards Will Reshape Buying Dynamics
As group practices and larger dental organizations continue to gain relative influence, purchasing decisions are likely to become more standardized, data-driven, and service-oriented. Multisite buyers often prefer consistent product lines, dependable service levels, and clear total cost models. At the same time, the revised ethical code and broader attention to commercial transparency will raise expectations for how suppliers and distributors interact with providers.
This creates an opportunity for companies that can professionalize their engagement model. Clear documentation, consistent service, ethical alignment, and channel discipline can become meaningful differentiators, especially in a market where trust influences repeat purchasing and referral patterns. The risk is that any lapse in compliance, supply reliability, or pricing transparency can have outsized reputational effects in a concentrated and relationship-driven market.
Risks and Uncertainties to Monitor
Several factors could alter the pace or shape of growth. Reimbursement policy changes, labor market shifts, and raw material cost volatility can influence both demand and margin trajectories. The modest month-over-month employment decline in dental offices in December 2025, even with positive annual growth, highlights that labor dynamics can fluctuate in ways that affect practice capacity and service models. Additionally, the concentration of revenue among leading players means that competitive responses from major incumbents can quickly reshape subcategories, particularly when they leverage broad portfolios and established distribution networks.
Dental Drug Market
Market participants should also watch the interaction between digital adoption and pricing. If clinicians increasingly expect integrated solutions, suppliers may need to invest more in compatibility, training, and service infrastructure, which can raise costs even as it strengthens differentiation. Balancing these investments against cost pressure will be a defining challenge over the forecast period.
Actionable Guidance for Decision Makers
The current environment rewards deliberate positioning. Different stakeholder groups face distinct priorities, but all can benefit from a clearer view of where growth, margin pressure, and competitive shifts are heading.
For Manufacturers and Product Companies
- Prioritize workflow-integrated innovation over isolated feature upgrades. Products that slot cleanly into digital and clinical processes are more likely to earn repeat adoption and reduce switching friction.
- Strengthen clinical evidence and practitioner education support. As choices multiply, clinicians will lean toward solutions with clear performance narratives and reliable training resources.
- Align commercial practices with evolving ethical and transparency expectations. Clear guidelines, consistent engagement, and compliant channel behavior can protect reputation and improve partner confidence.
For Investors and Strategic Planners
- Assess exposure to cost-sensitive segments versus higher-value equipment and specialized materials. Margin resilience may increasingly depend on portfolio mix and pricing power rather than on volume growth alone.
- Monitor distributor and group-practice dynamics as indicators of buying consolidation. Shifts in purchasing patterns can affect volume predictability, service requirements, and go-to-market economics.
- Track regulatory and reimbursement developments closely. Stable reimbursement that lags expenses can reshape demand patterns and influence which product categories gain traction.
For Distributors and Procurement Leaders
- Emphasize availability, pricing predictability, and service consistency. In an environment of rising supply prices, reliability and total cost clarity can be as important as unit price.
- Support standardization where it makes sense, while preserving flexibility for smaller or specialized practices. Different practice models value different purchasing experiences, and segmentation can improve satisfaction and retention.
- Use clear product information, digital selection tools, and compliant engagement practices to reduce friction and build trust across the supply chain.
The pace of change in the dental market makes timely, granular intelligence essential. Market-wide growth signals opportunity, but the practical decisions that determine competitive outcomes depend on segment-level detail, regional variation, pricing behavior, and product-level momentum. For leaders who need deeper segmentation data, company-specific benchmarks, and tailored recommendations aligned with their portfolio or investment thesis, the full research report provides a more detailed view of the market landscape and the strategic choices it presents.
As the sector moves from 2025 into the late 2020s and toward 2032, the winners will likely be those who treat efficiency, innovation, and commercial integrity as interconnected priorities rather than separate tasks. The market is expanding, but expansion alone does not guarantee advantage. Positioning, execution, and insight will determine who captures the most value from the opportunities ahead.
For detailed analysis of this topic, please visit the official page: Dental Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Optical Fiber Fusion Splicer Market: 6% CAGR Signals Shift to Asia Pacific
By PW Consulting, 2026-09-21
The Optical Fiber Fusion Splicer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
Market Trajectory and Scale
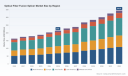
The optical fiber fusion splicer market has demonstrated consistent expansion over the past five years, reflecting the broader acceleration of fiber-optic infrastructure deployment worldwide. Revenue grew from approximately $163.15 million in 2020 to an estimated $215.0 million in 2025, representing a compound annual growth rate of roughly 6.0 percent over the historical period. This trajectory is expected to continue through the forecast horizon, with market revenue projected to reach $344.8 million by 2032. The steady upward path is underpinned by long-term capital expenditure commitments in telecommunications networks, data center interconnections, and industrial connectivity applications, all of which rely on precision fiber joining to maintain signal integrity and network reliability.
While the headline growth rate appears moderate, it masks important structural dynamics beneath the surface. The market is not expanding uniformly across all product categories or end-use segments. Single-fiber fusion splicers continue to dominate revenue contribution, reflecting their entrenched role in telecom backbone builds, premises networking, and field repair operations. Ribbon and other specialized splicer formats occupy a smaller but strategically important position, catering to high-density fiber routing scenarios where throughput and port density justify higher unit costs. This balance between volume-driven single-fiber demand and niche high-performance segments creates a dual-track revenue structure that rewards manufacturers capable of serving both mainstream and specialized deployment profiles.
Key Challenges and Inflection Points
Despite the favorable growth backdrop, the industry faces several structural challenges that are reshaping competitive priorities and investment decisions.
- Margin pressure from commoditization in mainstream segments: As single-fiber fusion splicers mature into standardized field tools, price transparency increases and differentiation narrows. Manufacturers that compete primarily on baseline functionality risk margin erosion unless they can bundle software, service, or operational efficiency gains that justify premium positioning.
- Technician skill gaps and deployment complexity: Fiber network densification, particularly in data center interlinks and rural broadband rollouts, places higher demands on installation speed and first-pass yield. Splicer platforms that require extensive manual calibration or steep operator training can become bottlenecks in labor-constrained markets, pushing buyers toward more automated or guided workflows.
- Regulatory and procurement fragmentation: Government and institutional purchasing processes introduce additional complexity. Classification decisions, standards recognition, and formal sourcing inquiries can accelerate or delay demand depending on how clearly equipment fits into approved procurement pathways. This fragmentation creates uneven demand signals across regions and customer segments, requiring suppliers to maintain flexible go-to-market strategies rather than relying on a single channel or geography.
These challenges are not purely defensive issues; they also define where value is shifting. Companies that reduce operator dependency, streamline field workflows, and align product positioning with procurement realities are better placed to convert market growth into durable share gains.
Key Drivers Shaping Market Dynamics
Technology Innovation and Workflow Automation
The most consequential driver in the optical fiber fusion splicer market is the shift from standalone hardware tools to integrated splicing platforms that reduce human intervention and improve repeatability. Recent product introductions illustrate this direction clearly. In May 2026, AFL Telecommunications LLC launched the Fujikura 100R Mass Fusion Splicer featuring Auto Placement Correction, a capability designed to detect fiber alignment automatically and reduce the need for manual operator adjustment. This type of functionality matters commercially because it shortens installation time, lowers the risk of costly rework, and makes high-volume splicing operations more predictable in field and central office environments.
The broader technology trend extends beyond alignment assistance. Splicer manufacturers are increasingly integrating cloud connectivity, diagnostic feedback, and maintenance-oriented features that support fleet management and remote troubleshooting. For telecom operators and enterprise network teams, these capabilities translate into better asset utilization and faster mean-time-to-repair. For manufacturers, they open recurring value streams through service contracts, software-enhanced features, and lifecycle support rather than relying solely on unit sales. In practical terms, innovation is moving from "can the splicer join fiber accurately?" to "can the splicer join fiber quickly, consistently, and with minimal skilled labor across a distributed fleet?"
Policy and Standards Environment
Policy and standardization activity is another important driver, though it often operates indirectly through procurement behavior and market credibility. Recognition of technical contributions at the international standards level can reinforce a company's positioning in quality-sensitive segments. For example, Sumitomo Electric Industries received the Industrial Standardization Activity Award from Japan's Ministry of Economy, Trade and Industry for contributions to IEC and ISO international standards in optical fiber fusion splicing technology. Such acknowledgment signals that splicing performance, interoperability, and testing methodologies are increasingly governed by formal benchmarks rather than ad hoc vendor specifications.
Regulatory classification also shapes market access. The U.S. Department of Commerce Bureau of Customs and Border Protection issued a tariff classification ruling placing the portable optical fiber fusion splicer under a Harmonized Tariff Schedule code associated with telecommunications equipment. While a single ruling does not transform the market on its own, it illustrates how equipment classification can influence import handling, procurement categorization, and compliance expectations. Companies that understand these classification and sourcing pathways are better equipped to navigate public-sector and institutional buying cycles without unexpected delays or administrative friction.
Demand-Side Shifts in Connectivity Buildout
Demand for fiber fusion splicing continues to be anchored by long-term connectivity requirements rather than short-term project spikes. Telecommunications deployment remains the dominant application context, driven by carrier network modernization, backhaul and fronthaul upgrades, and broadband reach extension. At the same time, data center and enterprise interconnect needs are contributing an increasingly meaningful share of activity as organizations seek higher bandwidth, lower latency, and more resilient fiber pathways between facilities and within campus environments.
What is changing is not the existence of demand, but its operational texture. Network builders are prioritizing deployment models that reduce labor dependency, improve splicing consistency across multiple crews, and support rapid restoration in the field. This favors equipment that can be deployed by smaller teams, integrated into repeatable process workflows, and maintained with minimal downtime. The practical implication is that demand growth is increasingly tied to total installation efficiency rather than splicer unit count alone. Buyers are more likely to reward platforms that help them meet project timelines and service-level expectations, especially when skilled technicians are scarce or deployment windows are compressed.
Supply Chain and Cost Structure Dynamics
Cost structures in the fusion splicer market are influenced by component availability, manufacturing scale, and the balance between hardware commoditization and value-added features. Splicers depend on precision optical, mechanical, and electronic subsystems, and any disruption in critical inputs can affect lead times and pricing. At the same time, the market's moderate concentration leaves room for multiple players to compete without a single dominant price setter, which sustains competitive tension across both global and regional suppliers.
For commercial strategy, this means that cost leadership alone is unlikely to be a durable differentiator unless paired with operational advantages that buyers can measure directly. Suppliers that can stabilize production, optimize logistics, and align pricing with total cost of ownership—such as reduced training time, fewer re-splits, and higher equipment utilization—tend to hold up better when input costs fluctuate or when end customers scrutinize project budgets more closely. The strategic opportunity lies in making cost part of a broader efficiency narrative rather than treating it as a standalone price competition.
Competitive Landscape and Leading Strategies
Company Positioning and Differentiation
The competitive field includes established Japanese manufacturers with deep telecom heritage, U.S. suppliers anchored in fiber and network infrastructure, and capable regional players with strong product focus in specific deployment contexts. Fujikura Ltd. remains closely associated with core alignment fusion splicer platforms used across telecom and enterprise applications, with models that emphasize low-loss splicing and connectivity features suited to both field and controlled-environment use. Sumitomo Electric Industries continues to position around high-speed core alignment splicers designed for field and long-haul installations, including tools with navigation and verification features that support challenging deployment conditions.
INNO Instrument Inc. has built a profile around rugged splicing platforms with ribbon fiber support and dual-camera guidance, targeting data center and high-density deployments where multiple fibers must be handled efficiently. OFS Fitel contributes to the market through fusion splicer products oriented to single-mode fiber splicing in telecom and enterprise networks, leveraging its broader optical fiber and component background. Furukawa Electric maintains a presence through core alignment splicers and related capabilities for carrier networks and emergency repair, with attention to both single-fiber and ribbon/mass splicing scenarios. AFL Telecommunications participates through splicer products linked to intelligent alignment controls and high-volume installation use cases, including mass fusion models designed to reduce operator intervention.
Worldwide Video Splicer Market
The differentiating thread across these players is not simply feature count, but how each company aligns product design with deployment reality. Some compete on precision and reliability for demanding long-haul or carrier-grade work. Others compete on ruggedness, high-density compatibility, or workflow automation for data center and enterprise environments. This segmentation matters because the same splicer is rarely optimal across all settings; buyer priorities shift depending on fiber count, environment, crew skill level, and service requirements.
Market Structure Evolution
The market remains relatively fragmented, with no single dominant concentration level among top participants. This fragmented structure supports ongoing competition and limits the risk of pricing power becoming overly centralized. At the same time, it encourages strategic divergence: some firms will push toward broader platform ecosystems with service, software, and lifecycle support, while others will concentrate on specialized product strengths or regional reach.
Several evolutionary patterns are worth watching. First, product launches are increasingly oriented toward reducing manual steps and improving repeatability, which raises the bar for what counts as a competitive field tool. Second, procurement activity from government or institutional buyers can shift short-term demand visibility and reward suppliers with clear compliance and sourcing readiness. Third, standards-related recognition and classification clarity can influence purchasing confidence, especially where buyers need to justify selections through formal specifications or procurement frameworks. Taken together, these dynamics suggest a market that will continue to support multiple credible players, but where share gains will increasingly depend on how well companies connect product capabilities to customer workflow outcomes.
Future Trend Outlook: 2026 to 2032
Trend 1: Automation as a Commercial Imperative
Over the next several years, automation features are likely to move from desirable enhancements to baseline expectations in many segments. Auto alignment detection, guided cleave verification, and reduced manual correction steps will become more central to product value propositions as deployment teams seek to standardize results across crews and locations. This trend carries a clear commercial opportunity: manufacturers that package automation with intuitive interfaces, maintenance diagnostics, and fleet-management compatibility can position themselves as partners in operational efficiency rather than as hardware vendors alone.
The associated risk is that automation expectations may outpace real-world usability. Features that look strong in specification sheets but are difficult to use under field conditions can undermine adoption. The winners are likely to be those who validate automation in practical deployment environments and tie it to measurable improvements in speed, consistency, and training burden.
Trend 2: Broader Demand Across Telecom and High-Density Interconnect
Demand growth will continue to be supported by telecommunications infrastructure, but the mix will broaden as high-density fiber environments gain importance. Data center interconnects, enterprise campuses, and dense urban fiber architectures create scenarios where splicing volume, repeatability, and fiber management complexity are all elevated. In these settings, ribbon-compatible and mass fusion capabilities can become more commercially relevant because they address throughput needs that single-fiber workflows struggle to meet efficiently.
The strategic opportunity here is to align product roadmaps and service offerings with the environments where splicing occurs most intensively. Suppliers that can demonstrate credible solutions for both mainstream telecom and high-density applications will be better positioned to capture demand across multiple project types rather than relying on a single pipeline.
Trend 3: Procurement Formalization and Standards-Linked Confidence
As public-sector and institutional buying becomes more structured, formal sourcing activity and classification clarity may increasingly influence purchase timing and supplier selection. Recent government sources sought notices and tariff classification rulings point to an environment where procurement readiness and standards alignment can affect market access. Companies that maintain documentation discipline, understand sourcing pathways, and can demonstrate consistency with recognized standards may find it easier to participate in structured buying processes.
Optical Fiber Patch Cord Market
The risk is that formalization can slow decision cycles or create barriers for suppliers less prepared for compliance-oriented purchasing. The opportunity is to treat procurement readiness as part of the product and go-to-market strategy, not as a back-office afterthought. In practice, this means clear product categorization, traceability, and specification support that make it easier for buyers to justify selections within formal acquisition frameworks.
PW Consulting Automotive & Machinery Research Center
Strategic Recommendations for Decision Makers
For Manufacturers and Product Strategy Teams
- Prioritize workflow outcomes over feature count. Design improvements around measurable field benefits such as reduced manual correction time, lower training requirements, and higher first-pass success, because these are the factors that buyers increasingly value in cost-conscious, labor-constrained environments.
- Build differentiation around total cost of ownership. Where hardware pricing is under pressure, emphasize service, lifecycle support, and operational efficiency gains that help customers justify purchase decisions beyond initial unit price.
- Prepare for procurement-aware selling. Maintain clear product classification understanding, specification support, and documentation practices that reduce friction in institutional and government-facing sales cycles.
For Investors
- Focus on companies with automation roadmaps tied to real deployment conditions. The most durable value creation is likely to come from suppliers that can translate features into repeatable field performance and fleet-level efficiency rather than from those competing mainly on incremental spec improvements.
- Watch demand mix, not just headline growth. Markets with a balanced base in telecom and expanding high-density interconnect needs may offer more resilient revenue streams than those dependent on a single deployment cycle.
- Assess competitive resilience through customer retention and service economics. In a fragmented market, the ability to maintain relationships through support quality, parts availability, and predictable uptime can be as important as product launches.
For Procurement and Network Operations Leaders
- Evaluate splicer platforms against total installation efficiency. Consider not only splice loss and accuracy, but also crew training burden, time to first splice, error recovery, and maintenance responsiveness, since these factors shape project throughput and service restoration.
- Align equipment selection with deployment context. High-density or mass-splicing environments may require different tooling priorities than routine single-fiber field repairs, so procurement criteria should reflect the actual mix of work the team will perform.
- Plan for lifecycle support and sourcing clarity. Equipment that fits cleanly into procurement pathways and comes with reliable support structures can reduce administrative and operational risk across multi-year deployment programs.
The optical fiber fusion splicer market is moving toward a phase where growth is increasingly defined by operational efficiency, procurement readiness, and the ability to serve both mainstream telecom and high-density interconnect environments. Companies and buyers that focus on these practical outcomes are better positioned to capture value as the market expands toward 2032. For decision makers seeking more detailed segmentation data, company-level assessments, and tailored commercial guidance, reviewing the complete research report can provide additional depth beyond the strategic trends outlined here.
For detailed analysis of this topic, please visit the official page: Optical Fiber Fusion Splicer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dicalcium Phosphate Market Insights: Decoding 5.0% CAGR Growth Drivers to 2032
By PW Consulting, 2026-09-21
Navigating the Dicalcium Phosphate Market: Strategic Imperatives for the Next Decade
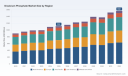
The global Dicalcium Phosphate market enters the late 2020s at a critical juncture. Between 2020 and 2025, the industry expanded from approximately $900 million to over $1.1 billion, reflecting sustained demand across feed, food, and pharmaceutical applications. Forward projections through 2032 indicate a trajectory toward $1.56 billion, underpinned by a compound annual growth rate of roughly 5.0 percent. These figures do not tell a simple growth story. They reveal a market undergoing structural realignment, where value creation increasingly depends on grade specialization, regulatory compliance, and supply chain resilience rather than volume alone.
Tricalcium Phosphate Market
Market Snapshot and Underlying Tensions
Historically, Dicalcium Phosphate benefited from predictable procurement cycles in animal nutrition and steady utilization in food fortification. The recent acceleration, however, has been uneven. Feed-grade volumes remain the largest share of total revenue, but food-grade and pharmaceutical-grade streams are gaining relative importance as downstream industries prioritize purity, traceability, and functional performance. The market remains moderately concentrated, with the top three players collectively controlling a substantial portion of output and the top five firms capturing the majority of traded supply. This concentration creates both stability for established buyers and friction for new entrants seeking scale.
Three structural tensions currently shape the operating environment. First, the industry must reconcile volume-driven economics with tightening quality thresholds. Feed applications demand cost efficiency, while food and pharmaceutical applications impose rigorous impurity limits, moisture control, and documentation standards. Second, geographic demand is shifting in ways that stress traditional logistics networks. Emerging agricultural intensification and expanding food processing capacity in Asia Pacific and Latin America are creating pull that legacy European and North American production hubs must route efficiently. Third, the sector faces margin pressure from raw material volatility, which interacts with regulatory compliance costs to reshape the profitability equation for mid-tier producers.
The practical implication is clear: competitive advantage no longer belongs to generic producers. It accrues to firms that can manage multiple grade specifications within the same facility, convert compliance into a commercial differentiator, and align production footprints with regional demand centers.
Key Drivers Reshaping the Market
Technology and Process Innovation
Advancements in precipitation control, drying, and particle engineering are redefining what Dicalcium Phosphate can deliver in end-use applications. Fine-tuning of crystal morphology and moisture content is improving flowability and compressibility for tablet formulations, while also supporting consistent phosphorus bioavailability in feed premixes. Producers that invest in process automation and inline quality monitoring are better positioned to reduce batch variability, minimize rework, and meet the increasingly strict documentation expectations of food and pharmaceutical buyers. Over time, these operational improvements translate into lower total cost of ownership for customers, which is becoming a decisive factor in vendor selection.
PW Consulting
Regulatory and Policy Environment
Regulatory frameworks are acting as both a barrier and a catalyst. In the European Union, stringent purity thresholds for feed additives have elevated quality expectations across the supply chain, effectively filtering out producers that cannot sustain consistent compliance. Meanwhile, food and pharmaceutical applications are governed by recognized monographs and food additive standards that define limits for heavy metals, microbial load, and related substances. These frameworks increase the cost of entry, but they also create a durable moat for capable manufacturers. In markets where regulatory harmonization is advancing, compliant producers can command premium positioning because buyers treat quality assurance as a non-negotiable input to their own brand risk management.
Demand-Side Behavior Shifts
The demand picture is changing on both the animal nutrition and human nutrition fronts. In feed, the growth of intensive livestock and aquaculture operations is driving consistent phosphate requirements, but buyers are also more selective, favoring suppliers that can guarantee specification stability across seasons and shipments. In food fortification and supplements, rising awareness of bone health, mineral supplementation, and clean-label sourcing is encouraging manufacturers to seek Dicalcium Phosphate grades with documented purity and predictable functionality. Pharmaceutical and related applications continue to value excipient performance and regulatory traceability. Across these segments, the common thread is a shift from price-first procurement toward value-first partnerships, where reliability, certificate-of-analysis consistency, and responsiveness matter as much as unit cost.
Worldwide Diethyl Chlorophosphate Market
Supply Chain and Cost Structure Dynamics
Phosphate rock remains the dominant cost input in Dicalcium Phosphate production, with estimates placing it at roughly 60 to 70 percent of operating expenses. The sensitivity of margins to raw material prices is therefore significant. Recent commodity data shows mine-level pricing hovering in the vicinity of $80 per metric ton on an f.o.b. basis, while domestic production volumes in major supplying countries remain substantial. This cost structure favors producers with secure rock access, efficient beneficiation, and the ability to hedge or contract feedstock intelligently. At the same time, logistics costs and regional energy dynamics can either amplify or dampen the impact of raw material prices. Companies that design supply chains around proximity to demand, flexible routing, and integrated quality systems are better able to protect margins during cycles of input volatility.
Competitive Landscape and Strategic Positioning
The competitive field is diversified by geography and by grade focus. Some manufacturers emphasize branded excipients and specialty formats for food, beverage, supplement, and tablet applications, building reputation around consistency and application support. Others concentrate on anhydrous and feed-grade volumes, leveraging multi-site production across Europe, North Africa, and South America to serve industrial and animal nutrition customers at scale. Additional players in China, India, and Japan maintain a strong presence in feed, food, and pharmaceutical grades, with several firms oriented toward active pharmaceutical ingredient and dihydrate formats. This mix creates a market where scale, specialization, and regional reach each provide distinct advantages.
Differentiation Levers Among Leading Players
Leading firms tend to differentiate along three axes. The first is grade breadth: the ability to serve feed, food, and pharmaceutical requirements from integrated operations reduces customer burden and increases stickiness. The second is compliance and documentation: robust quality systems, traceable sourcing, and alignment with recognized monographs and food/feed standards allow producers to enter more sensitive applications. The third is geographic fit: locating production closer to key demand clusters shortens lead times, reduces freight exposure, and improves service levels. When these levers are combined, suppliers transition from commodity vendors to application partners, which is where pricing power and long-term contracts become achievable.
Evolution of the Market Structure
The landscape is likely to trend toward selective consolidation among mid-tier producers who lack scale or compliance depth, while specialized players continue to carve out niches in food-grade and pharmaceutical-grade segments. Greenfield and expanded capacity announcements, such as recent initiatives tied to animal feed supplement production with regional government support, indicate that new entrants and existing players alike see room for targeted investment where demand is growing and logistics align. At the same time, the presence of multiple capable suppliers in Asia and India suggests that competitive intensity will remain strong on price and availability, pushing differentiated players to compete more explicitly on quality, service, and specification control. The net effect is a market that is not simply consolidating, but stratifying: commodity volumes remain contested, while higher-value grades increasingly reward precision and credibility.
Forward Outlook: Three Trends to Watch
Trend One: Grade Specialization as the New Growth Engine
Over the next three to five years, incremental growth is expected to come less from undifferentiated volume and more from higher-purity grades and application-tailored formats. Food fortification and pharmaceutical-related uses are likely to outpace pure feed growth rates in relative terms, driven by stricter quality expectations and demand for consistent functional performance. For producers, this means the most resilient revenue streams will be those supported by documented purity, controlled particle characteristics, and reliable certificate-of-analysis outcomes. The commercial opportunity lies in building grade-specific capacity and marketing supply as a quality-assured input rather than a bulk commodity.
Trend Two: Regional Rebalancing of Supply and Demand
Demand growth is expected to remain strongest where food processing, animal nutrition, and supplement manufacturing are expanding rapidly, while established markets will focus on replacement, reformulation, and premiumization. This rebalancing encourages investment in production and blending capabilities that are closer to emerging demand hubs. It also rewards logistics agility, because buyers increasingly value shorter, more predictable supply paths. Firms that align footprint decisions with regional demand trajectories can reduce transit risk, improve service levels, and capture share from distant suppliers that are more exposed to freight and timing variability.
Trend Three: Compliance as a Commercial Asset
Regulatory scrutiny and buyer diligence are unlikely to ease. The practical consequence is that compliance infrastructure, audit readiness, and documentation consistency will become explicit buying criteria rather than background requirements. Producers that institutionalize quality assurance and can demonstrate alignment with food and feed standards will find it easier to enter and retain sensitive applications. The risk is equally clear: any lapse in specification control or documentation can quickly erode customer trust in these grades. Organizations that treat compliance as a strategic capability rather than a cost center will be better positioned to defend margins and expand into higher-value channels.
Strategic Actions for Decision Makers
For manufacturers, the priority is to clarify grade strategy and invest where differentiation is defensible. Facilities that can flexibly serve feed, food, and pharmaceutical requirements with rigorous quality controls will capture more resilient demand than those locked into a single price-competitive segment. Process automation, inline monitoring, and clean documentation workflows should be treated as enablers of premium positioning, not merely operational improvements. Where raw material exposure is high, securing reliable rock supply and designing efficient production routes can help stabilize margins during price swings.
For investors, the opportunity is to evaluate exposure through the lens of grade mix and compliance depth rather than total capacity alone. Assets tied to higher-purity food and pharmaceutical applications, or to regionally balanced production footprints, tend to offer more durable growth profiles than undifferentiated volume plays. Due diligence should emphasize feedstock arrangements, quality system maturity, and customer concentration in sensitive applications, because these factors determine whether a business can convert market growth into sustainable returns.
For procurement and supply chain leaders, the mandate is to reweight supplier evaluation toward specification reliability, documentation quality, and service predictability. Multi-grade sourcing strategies can reduce single-supplier dependency while maintaining access to premium materials when needed. Establishing clear acceptance criteria, audit expectations, and contingency routing will help protect production continuity in food and pharmaceutical contexts where variability carries disproportionate risk. In feed applications, total cost of ownership should incorporate not only unit price but also consistency, lead-time reliability, and the cost of non-conformance.
The market’s next phase will reward participants who can read these shifts early and act on them with discipline. While the headline trajectory points to steady expansion, the real strategic value lies in understanding how grade demand, regulatory intensity, and regional supply dynamics interact at the segment level. For decision makers seeking a fuller picture of sub-segment sizes, regional pathways, and company-level positioning to inform investment and procurement choices, the detailed research report provides the granular data and customized analysis needed to move from broad direction to executable plan.
For detailed analysis of this topic, please visit the official page: Dicalcium Phosphate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
CNT Market’s 14.88% CAGR Trajectory: What Structural Shifts Are Really Driving It
By PW Consulting, 2026-09-21
Carbon Nanotube Market Strategic Trends and Commercial Opportunities: A 2025–2032 Outlook
Carbon nanotubes have moved beyond laboratory promise into a phase of commercial scaling defined by structural demand, repeated capacity expansions, and increasing integration into mainstream material portfolios. Over the historical period from 2020 through 2025, the global carbon nanotube sector expanded from roughly 500 million USD to approximately 1.75 billion USD, reflecting a marked acceleration in the later years of the timeline. Current forecasting places the market on a 14.88 percent compound annual growth trajectory through 2032, with revenue projected to reach 4.59 billion USD by the end of the forecast window. This growth curve is not linear. It reflects a bimodal pattern in which early development years gave way to a step-change in commercialization as battery manufacturers, electronics assemblers, and advanced composite engineers began standardizing carbon nanotube additives into production processes.
For executives and investors, the central question has shifted from whether carbon nanotubes will scale to how the value chain will organize itself around scale. The answer increasingly depends on how quickly producers can translate capacity additions into consistent quality, how industrial buyers absorb new formulations without disrupting existing lines, and how regulatory frameworks mature around exposure, handling, and reporting requirements.
Market Context and Critical Inflection Points
The market is experiencing a transition from fragmented early-stage adoption to a more concentrated, application-led growth structure. Concentration among the leading participants remains significant, with the top three firms accounting for a substantial share of total revenue and the top five approaching a majority of market activity. This concentration is not accidental. It reflects the technical complexity of producing carbon nanotubes at consistent purity, the capital intensity of expanding production, and the importance of established supplier relationships in validation-heavy industries such as electronics, energy storage, and structural composites.
Two inflection points are shaping the near-term trajectory. The first is the move from pilot-scale validation to volume integration, especially in batteries and conductive formulations. As production capacity expands across multiple geographies, the limiting factor is no longer whether carbon nanotubes can be made, but whether dispersion quality, dust control, and batch-to-batch consistency can meet industrial acceptance thresholds at scale. The second inflection point is the growing intersection of nanomaterials with regulatory oversight. Carbon nanotubes are increasingly treated as a distinct class requiring documented risk and exposure data, which raises the compliance burden for manufacturers and processors while simultaneously reinforcing the advantage of established producers who already operate with structured quality systems and reporting processes.
The third pressure point is cost-driven selectivity among buyers. As more suppliers enter the market and capacity grows, industrial users are becoming more discerning about grade, dispersion format, and performance claims. This is a healthy maturation signal, but it also means that generic product offerings will face margin compression. The commercial battleground is now differentiating by capability rather than by availability alone.
Core Drivers Reshaping the Carbon Nanotube Market
Technological Innovation and Performance Breakthroughs
The most consequential technical shift is the migration of carbon nanotubes from niche enhancement materials to standard constituents in demanding applications. High-conductivity grades and tailored dispersions are now being positioned for lithium-ion battery anodes and cathodes, conductive plastics, and advanced composite systems. The strategic value lies in incremental but compounding performance gains: lower internal resistance, improved charge-transfer pathways, stronger mechanical reinforcement at lower loading levels, and formulation designs that reduce processing complexity.
Recent progress in dispersion engineering and co-catalyst development illustrates this trend well. Rather than chasing raw capacity alone, leading producers are increasingly focused on formulations that improve dispersibility, lower dust generation, and simplify downstream integration. That matters because industrial adoption often hinges on manufacturability. A material that delivers exceptional lab properties but is difficult to handle at scale will lose to a slightly less exotic alternative that behaves predictably in continuous production environments.
Policy and Regulatory Environment
Regulatory dynamics are becoming a defining part of the operating landscape. Under evolving chemical oversight frameworks, manufacturers, importers, and processors of carbon nanotubes are increasingly expected to submit risk and exposure data, and some jurisdictions have introduced reporting thresholds relevant to production and handling facilities. State-level surveys have also identified where carbon nanotubes are used across semiconductor, composite, and nanotechnology manufacturing sites, which signals a more active monitoring environment.
This regulatory trajectory has two practical implications. First, it adds a layer of compliance cost and administrative rigor, particularly for new entrants or smaller producers with less mature environmental, health, and safety infrastructure. Second, it creates a differentiation advantage for producers that can provide documented traceability, controlled manufacturing conditions, and formulation support that simplifies downstream compliance. In effect, regulatory maturation is pushing the market toward quality assurance as a strategic asset rather than a back-office function.
Worldwide Carbon Nano Cold Cathode Tube Market
Demand-Side Shifts in Electronics, Energy, and Advanced Materials
Demand is being pulled by several converging industrial priorities. In electronics and semiconductors, the push for more efficient conductive pathways and miniaturized components is creating steady interest in nanotube-based inks, formulations, and functional materials. In energy storage, battery performance, cycle life, and thermal behavior remain central engineering concerns, which makes conductive additives attractive when they can be integrated without compromising existing manufacturing economics. In structural composites and polymer systems, formulators are looking for reinforcement and conductivity improvements that can be achieved at practical loading levels without undermining processability.
What makes this phase different is the combination of volume and specificity. Buyers are not simply asking for carbon nanotubes; they are asking for grades that match particular processing routes, dispersion formats that minimize disruption, and performance consistency that survives scale-up. As a result, demand growth is increasingly tied to supplier capability in application engineering, not just tonnage.
Supply Chain and Cost Structure Dynamics
The cost structure of the market is evolving as production scales and geographic diversification increases. Capacity expansions across multiple regions are reshaping supply resilience, while the industrial focus on dispersion quality and low-dust formulations is changing what counts as a commercially viable product. In practical terms, the total delivered value of a carbon nanotube offering now depends on more than purity and price per kilogram. It includes the downstream burden of handling, dispersion, integration, and performance validation.
PW Consulting
Supply chains are also becoming more application-specific. Producers that can offer standardized dispersion formats and formulation support reduce the adoption friction for buyers, while those operating only at the powder level may face longer qualification cycles. This is gradually shifting the competitive center of gravity from raw production alone toward integrated material solutions.
Competitive Landscape and Strategic Positioning
The competitive field is increasingly defined by scale, application focus, and formulation capability. A small group of major producers is driving much of the capacity expansion and product standardization activity, while a broader set of specialized firms competes in high-purity, electronics-grade, or research-oriented segments. This dual structure is important: volume leadership is becoming more valuable in battery and conductive-additive markets, while specialty differentiation remains essential in semiconductors, printed electronics, and high-specification composites.
Several strategic patterns are visible across the leading participants.
-
Vertical integration around capacity and geography is a common theme. Firms are expanding plant networks to support growing demand from energy storage and conductive applications, while also positioning themselves closer to key downstream markets. This reduces logistical friction and strengthens supply reliability for large buyers.
-
Formulation and dispersion capability is becoming a differentiator. The ability to supply ready-to-use dispersions, low-dust grades, and iron-free or otherwise tailored formulations matters because it shortens adoption cycles and simplifies integration into battery and polymer processes.
-
Product-line diversification is widening the addressable market. Leading producers are building portfolios that span battery additives, conductive plastics, coatings, and composite reinforcements, which helps buffer demand volatility across end-use sectors.
Boron Nitride Nanotubes (BNNT) Market -
Specialization remains a viable path. Companies focused on high-purity semiconducting grades or research-grade materials continue to play an important role in enabling emerging uses, particularly where performance specificity outweighs volume considerations.
Capacity expansion is a dominant theme in recent industry activity. One major producer commissioned an additional facility that lifted total operating capacity by a significant margin, reflecting a deliberate push to support battery and conductive additive demand. Another volume-focused producer initiated a new cathode material project with phased capacity coming online in the near term. A leading single-walled carbon nanotube producer scaled dispersion capacity substantially through partner-based expansion in China. These moves are not isolated. They indicate a market where producers are racing to secure both volume and application proximity.
The competitive evolution is also likely to produce consolidation pressure over time. As the market matures, larger, well-capitalized producers with multi-application portfolios and strong formulation capabilities will be better positioned to absorb demand cycles and compliance requirements. At the same time, specialized entrants can still thrive where performance requirements are highly specific and switching costs are high. The net effect is a market that is simultaneously consolidating at the top and fragmenting in niche segments where precision and technical support matter more than scale.
Forward Trends and Strategic Implications for 2026–2032
Trend One: Battery and Energy Storage Applications Will Anchor Volume Growth
Energy storage remains one of the most important demand anchors for carbon nanotubes, particularly as conductive additives become more embedded in battery electrode design. The practical opportunity is not only in improved conductivity, but also in engineering gains such as reduced internal resistance and better material integration. As battery manufacturers continue to optimize performance and throughput, nanotube-based additives are likely to see broader acceptance where they can demonstrate measurable process and performance benefits.
The commercial implication is clear: producers that can consistently supply battery-grade formulations with strong quality control and application support will capture disproportionate value. Buyers, in turn, should evaluate supplier capability in dispersion design and qualification support rather than treating carbon nanotubes as a commodity input.
Trend Two: Regulatory and Handling Standards Will Reshape Sourcing Decisions
As reporting expectations and oversight mechanisms become more defined, sourcing decisions will increasingly factor in compliance readiness, exposure documentation, and handling characteristics. This trend does not necessarily slow the market, but it does raise the bar for operational maturity. Producers with structured quality systems and transparent documentation will have an advantage, while less organized participants may find it harder to enter regulated supply chains.
For industrial users, this means that supplier selection should incorporate compliance, safety, and handling considerations alongside performance metrics. For producers, it means that documentation, traceability, and formulation support are no longer optional enhancements; they are part of commercial competitiveness.
Trend Three: Formulation, Dispersion, and Application Engineering Will Outperform Raw Powder Competition
As capacity grows, the market will increasingly reward solutions that reduce integration risk. Dispersion quality, dust control, batch consistency, and ready-to-use formats will become more valuable than price alone. This is a typical maturation pattern in advanced materials: early competition centers on basic availability, and later competition centers on reliability, usability, and performance assurance at scale.
Strategically, this favors companies that invest in formulation know-how and customer-facing technical support. It also creates opportunities for partnerships between material producers and downstream formulators who can co-develop application-specific solutions.
Risks and Uncertainties
Several uncertainties could shape the pace and distribution of growth. Regulatory requirements may evolve faster than some producers can adapt, especially if exposure and risk assessment expectations expand. Overcapacity in certain grades could pressure margins if demand does not keep pace with new capacity, particularly where differentiation is weak. Application adoption may also be slower than anticipated in some sectors if validation cycles remain long or if alternative materials improve rapidly. Finally, supply chain concentration in specific geographies could create vulnerability if logistics, trade conditions, or local operating environments shift.
These risks do not undermine the broader growth outlook, but they justify disciplined capacity planning, strong application engineering, and careful attention to regulatory readiness.
Actionable Guidance for Decision Makers
For manufacturers and product developers, the priority is to treat carbon nanotube selection as an integration decision, not just a material purchase. Qualifying a supplier should include dispersion behavior, dust and handling characteristics, batch consistency, and the supplier's ability to support scale-up. Where feasible, co-developing formulations with experienced producers can reduce qualification time and improve performance predictability in production environments.
For investors, the most durable value creation is likely to come from companies that combine scalable capacity with formulation strength and multi-application portfolios. Pure capacity expansion without application support may generate volume but not necessarily margin resilience. Due diligence should therefore assess not only capacity milestones, but also dispersion capability, customer qualification progress, regulatory readiness, and the degree to which a company is embedded in high-value demand segments such as batteries and conductive materials.
For procurement and sourcing leaders, the market now rewards technical evaluation over simple price comparison. Evaluation criteria should include documented quality systems, handling and safety posture, dispersion formats, and track record in the specific application of interest. Diversifying across suppliers with different strengths can also reduce exposure to single-source risk, particularly where supply is concentrated or where regulatory and compliance expectations are tightening.
As the market moves deeper into this phase of scaling and standardization, the competitive edge will belong to organizations that can align material capability with operational reality. The most useful next step is to map current application requirements against supplier capabilities, identify where dispersion, quality, and compliance readiness matter most, and prioritize engagement with producers that can demonstrate measurable integration value rather than generic availability. Detailed segmentation data, supplier benchmarking, and application-specific pathway analysis can further sharpen these decisions and support more targeted commercial strategy.
For detailed analysis of this topic, please visit the official page: Carbon Nanotube (CNT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
2 Blade Benchtop Jointer Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-21
Overview
The 2 Blade Benchtop Jointer Market encompasses compact, versatile woodworking tools designed for precise edge and face jointing on small to medium-sized workpieces. These devices are essential in woodworking shops, manufacturing facilities, and custom cabinetry operations, providing accurate and efficient surface preparation. Their core functionalities include achieving smooth, flat edges and faces, which are critical for high-quality assembly and finishing.
The 2 Blade Benchtop Jointer Market plays a vital role in supporting modern industries by enabling efficient material preparation and ensuring consistent quality. These jointers are integral to furniture manufacturing, carpentry, and DIY projects, where precision is paramount. The market size and growth are driven by increasing demand for compact, user-friendly equipment, making the market a key component in industrial and craft applications.
Market Size and Growth
The current market value for the 2 Blade Benchtop Jointer Market is estimated at around USD 250 million. Over the next 7 to 10 years, it is projected to reach approximately USD 400 million, reflecting a compound annual growth rate (CAGR) of about 6%. Growth drivers include rising demand for small-scale woodworking tools, technological advancements, and expanding end-user applications in emerging markets.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2030
Key Drivers
• Increasing adoption of compact woodworking tools in small and medium enterprises
• Technological innovations enhancing precision and ease of use
• Growing DIY and home improvement trends
• Expansion of woodworking industries in emerging economies
Restraints
• High competition from alternative jointing solutions
• Technical limitations in achieving higher precision with small blades
• Regulatory standards for safety and emissions
• Cost constraints for small-scale manufacturers
Segmentation
• By Type: Fixed, Adjustable
• By Deployment: Desktop, Portable
• By Enterprise Size: Small, Medium, Large
• By End User: Furniture Makers, Carpenters, DIY Enthusiasts, Educational Institutions
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America shows steady demand driven by a strong DIY culture and technological adoption in manufacturing. Europe’s market benefits from advanced woodworking industries and strict quality standards, fostering innovation. The Asia-Pacific region is experiencing rapid growth, fueled by expanding construction and furniture sectors, alongside rising urbanization. Latin America’s market remains niche but is slowly adopting modern benchtop jointers. The Middle East & Africa are emerging markets with increasing interest in local craftsmanship and industrialization.
Opportunities
• Expansion in emerging markets such as India and Southeast Asia
• Integration of smart technology and automation features
• Development of lightweight, portable models for mobility-focused applications
• Adoption in educational and training institutions for skill development
Key Companies
JET Tools, Grizzly Industrial, Powermatic, Laguna Tools, Delta Power Equipment, WEN, Bosch, Makita, Dewalt, Festool, Scheppach, King Industrial
Conclusion
The overall outlook for the 2 Blade Benchtop Jointer Market remains positive, with long-term growth potential driven by technological innovation and expanding end-user applications. As industries seek compact, efficient solutions for precise woodworking, the market’s strategic importance will continue to grow. The market presents significant opportunities for industry players to capitalize on emerging trends and regional expansion, ensuring sustained growth over the coming years.
Related Reports
Induction Heating Soldering Station Market , Size Share and Analysis | Report 2033
Laboratory Gel Imager Market , Size Share and Analysis | Report 2033
End Gripper Market , Size Share and Analysis | Report 2033
Robotic Seam Tracking System Market , Size Share and Analysis | Report 2033
Welcome Robot Market , Size Share and Analysis | Report 2033
Lightweight Loitering Munitions Market , Size Share and Analysis | Report 2033
Portable Sound Intensity Probe Market , Size Share and Analysis | Report 2033
Rotary Steerable Tools Market , Size Share and Analysis | Report 2033
Pigment And Dye Inkjet Label Printers Market , Size Share and Analysis | Report 2033
Industrial Color Label Printer Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
SPD Market Insights: Why 6.98% CAGR and $344.8M Value Redefine 2026 Growth
By PW Consulting, 2026-09-21
The Surge Protection Device Market at a Strategic Crossroads: Growth, Regulation, and the Shift Toward Integrated Infrastructure Protection
The global surge protection device (SPD) market has entered a phase of steady expansion, with total revenue crossing the $215 million mark in 2025 and a projected compound annual growth rate of 6.98 percent through 2032. The trajectory reflects a market that has evolved from a peripheral electrical accessory into a core component of resilient power infrastructure. Between 2020 and 2025, revenue climbed from approximately $163 million to $215 million, a pace that accelerated as building codes tightened, industrial automation expanded, and end users grew more sensitive to equipment downtime. Looking ahead, the market is expected to scale toward roughly $345 million by 2032, driven by a blend of regulatory mandates, electrification trends, and a structural shift toward smarter, more visible protection devices. Yet growth alone does not guarantee profitability or competitive advantage. The SPD landscape is shaped by a fragmented supplier base, shifting cost dynamics, and a regulatory environment that increasingly rewards devices with clear end-of-life signaling and fail-safe performance. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but how value is being captured across regions, product categories, and end-use segments, and where strategic positioning can create durable differentiation.
A Market Characterized by Broad Adoption and Concentrated Competition
The overall market size has grown consistently over the past half-decade, with the most pronounced step-up occurring between 2022 and 2025. That acceleration aligns with a broader push toward protective infrastructure in both new construction and retrofit projects, as well as increased awareness of transient overvoltage risks in sensitive industrial and commercial environments. The forecast period through 2032 points to continued expansion, though the pace suggests a maturing market rather than a hypergrowth phase. Revenue growth is expected to be supported by higher penetration in industrial and commercial applications, where the cost of downtime and equipment damage far exceeds the upfront expense of protection devices. At the same time, residential adoption is expanding more gradually, constrained by installation complexity and cost sensitivity among homeowners.
Competition in the SPD market remains moderately concentrated, with the top three firms accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. This concentration level indicates that while established players hold meaningful share, a long tail of regional and specialized manufacturers continues to compete on price, application-specific engineering, and local service relationships. The market structure creates both opportunity and vulnerability. Incumbents with broad product portfolios and strong compliance credentials can leverage scale and brand trust, while smaller firms can win in niche segments by addressing specific signal-level protection, hazardous-area needs, or localized regulatory requirements. The net effect is a market where differentiation is increasingly tied to integration, certification agility, and lifecycle visibility rather than standalone surge suppression performance alone.
Key Challenges and Inflection Points Shaping the Market
Several structural pressures are redefining how SPDs are specified, purchased, and maintained. The first is the growing emphasis on end-of-life visibility and proactive maintenance. Regulatory expectations and engineering best practices are pushing devices toward clear status indication, remote monitoring, and fail-safe disconnection. This shift is changing procurement criteria: buyers are no longer evaluating SPDs solely on surge current ratings and certification, but also on how easily a device can be inspected, replaced, and integrated into maintenance workflows. The second challenge involves cost dynamics at the installation and ownership level. Whole-house and commercial panel-mounted SPDs typically require professional electrician labor, which adds meaningful upfront expense and can slow adoption in price-sensitive residential and small commercial segments. At the same time, energy and raw material cost pressures are being passed through the supply chain, raising the sticker price of premium units and creating a tension between protection quality and budget constraints. The third inflection point is the regulatory and standards environment itself. Updated editions of key safety and performance standards are reshaping product design requirements, particularly around testing, classification, and lifecycle behavior. Manufacturers must navigate a landscape where compliance is not static; it evolves with each standards cycle, affecting product roadmaps, certification timelines, and competitive parity across regions. Together, these forces are moving the market from a transactional hardware business toward a more service-aware, compliance-driven, and integration-focused market.
Worldwide Ethernet Surge Protector Market
Key Drivers of Market Change
The market's trajectory is being shaped by four interlocking drivers: technological innovation, regulatory momentum, shifting demand-side behavior, and supply-side cost structures. Each driver influences not only volume growth but also the mix of products that win in different applications.
Technological Innovation: From Standalone Suppression to Integrated, Intelligent Protection
Innovation in SPDs is increasingly centered on integration, miniaturization, and lifecycle management rather than raw surge-handling capability alone. Modular and plug-in architectures are reducing installation friction by enabling faster replacement and panel-level integration without extensive rewiring. Narrow-profile designs are gaining traction in space-constrained distribution boards and control panels, where engineers must balance protection with physical layout constraints. At the device level, thermally protected MOV-based solutions and gas discharge tube combinations continue to evolve, with an emphasis on fail-safe disconnection that prevents a degraded device from becoming a hazard after repeated stress events. Equally important is the move toward end-of-life signaling and remote indication. As maintenance teams face higher labor costs and more complex asset portfolios, SPDs that can communicate status or provide clear visual indicators are becoming more valuable because they reduce inspection uncertainty and support planned replacement. This trend is especially relevant in commercial and industrial environments, where downtime avoidance is a primary purchase driver and where SPDs are increasingly specified as part of a broader power quality and resilience strategy rather than as isolated hardware.
Policy and Regulatory Environment: Standards as a Design and Competitive Force
Regulatory frameworks are no longer just compliance checkpoints; they are actively shaping product architecture and procurement standards. Updated editions of UL 1449 have reinforced expectations around end-of-life visibility, pushing manufacturers to design devices with clearer status feedback and more predictable maintenance behavior. Complementary updates to IEC standards for low-voltage AC SPDs have refined performance parameters, making it easier to compare devices across international supply chains while also raising the bar for consistent test compliance. In parallel, electrical code cycles and regional building requirements continue to influence where SPDs are mandated or strongly recommended, particularly in new construction and major renovations. The practical effect is twofold. First, compliance credentials are becoming a more significant competitive moat, because certification timelines and test coverage can delay product launches and affect market access. Second, specifiers are increasingly writing requirements around lifecycle behavior and maintenance readiness rather than surge rating alone, which rewards manufacturers that can demonstrate robust design, clear documentation, and reliable post-event behavior.
Demand-Side Shifts: Electrification, Downtime Sensitivity, and Professionalization of Installation
Demand is being reinforced by several structural changes in how power is consumed and protected. Industrial automation, data-dependent commercial operations, and the proliferation of sensitive electronics have raised the cost of transient overvoltage events, making protection a more visible line item in facility planning. In commercial and industrial settings, SPDs are increasingly bundled into broader power distribution and switchgear discussions, which shortens specification cycles when devices are already aligned with recognized panel or switchgear platforms. At the same time, installation patterns are shifting toward a more professionalized model. Whole-house and larger commercial installations often require qualified electricians, and that labor requirement introduces both cost and scheduling considerations for end users. As a result, demand is strongest where the protection value is easy to quantify, where installation can be streamlined, or where devices are integrated into equipment that is already being purchased for other reasons. Residential demand is growing more slowly, partly because the value proposition must overcome both cost sensitivity and installation friction, though it is supported by broader home resilience trends and insurance-related awareness.
Supply Chain and Cost Structure: Material Pressures, Pricing, and Value Perception
On the supply side, energy costs and raw material prices have been moving through the value chain, affecting both manufacturer margins and end-user pricing. Premium surge protection devices are not immune to these pressures, and in some cases the price increase has created hesitation among cost-conscious buyers. That dynamic is important because it can widen the gap between basic and advanced devices, potentially slowing adoption of higher-specification products unless their value is clearly communicated. At the same time, periodic maintenance and component replacement introduce recurring cost considerations, especially where maintenance teams must inspect and replace elements such as MOVs or gas discharge tubes over time. These factors are nudging the market toward designs that reduce inspection burden, simplify replacement, and provide better visibility into device health. The broader implication is that cost is no longer just an upfront purchase decision; it is increasingly a total-cost conversation that includes installation labor, maintenance effort, downtime risk, and the reliability of end-of-life handling.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a group of large, diversified electrical and power management companies, alongside specialized players with strong application-specific engineering. The market's moderate concentration suggests room for both broad-portfolio scale play and targeted differentiation. Several recent product and documentation moves illustrate how leading firms are positioning themselves.
Incumbent Strategies: Integration, Compliance Breadth, and Application-Specific Solutions
Schneider Electric has emphasized integration into commercial and industrial distribution boards, extending plug-in SPD offerings that fit into existing panel ecosystems without requiring additional bolt-on enclosures or upstream devices. The strategic intent is clear: make surge protection easier to specify and install by aligning it with recognized load centre and panel platforms, while also improving visibility through end-of-life monitoring and remote indication. This approach targets the commercial and industrial segments where downtime avoidance and maintenance planning matter most. Siemens has taken a related but distinct path, embedding ground reference monitoring into low-voltage switchgear and panels and positioning residential and commercial SPD families as part of a broader protection and power distribution conversation. By tying SPD functionality closer to the equipment already present in the system, Siemens is reinforcing an integrated-infrastructure narrative rather than treating surge protection as an add-on. Eaton continues to focus on high short-circuit current ratings and UL 1449 compliance within power distribution systems, UPS, and switchgear, appealing to buyers who want protection tightly coupled with rated distribution equipment and clear compliance credentials. ABB offers a broad type coverage across Type 1, Type 2, and Type 3 devices, including modular and industrial overvoltage ranges aligned with IEC and UL standards, which supports customers seeking multi-tier protection across different installation points. Mersen has concentrated on thermally protected, fail-safe designs and updated its technical documentation to reflect current UL 1449 and NEC expectations, signaling an emphasis on lifecycle safety and code-aligned specification support. Phoenix Contact has extended its surge protection range toward process automation, measurement and control signals, and hazardous-area environments, including ultra-narrow modular formats and designs optimized for industrial Ethernet and emerging communication protocols. This strategy targets the more specialized end of the market, where space constraints, signal integrity, and environmental requirements create higher engineering barriers.
The pattern across these players is not simply broader product lines; it is a strategic move toward integration points where protection can be specified more naturally, maintained more easily, and justified more clearly. Devices that fit into established panel systems, communicate status, or address signal-level protection in demanding environments are gaining traction because they reduce friction in both specification and operation.
Market Evolution: Integration, Specialization, and the Competitive Middle
The competitive landscape appears to be evolving along three axes. First, there is a push toward integration with existing infrastructure, whether in load centres, switchgear, UPS, or automation panels. This reduces installation burden and improves specification flow, but it also raises the importance of platform compatibility and cross-product validation. Second, there is continued specialization in high-value niches such as signal-level protection, hazardous-area environments, and narrow-profile modular devices. These segments reward engineering depth and can command stronger margins when the application is clearly defined. Third, the market's moderate concentration leaves space for regional and application-focused competitors to compete on service, price, and local specification relationships, especially where procurement teams value responsiveness and localized support. The likely outcome over the next few years is not a simple shakeout, but a more layered competitive environment in which broad incumbents compete on integration and compliance breadth, specialists compete on application performance and environmental fit, and regional players compete on service and speed. Success will increasingly depend on how well a company can align product design, certification readiness, and lifecycle messaging with the way buyers actually specify and maintain SPDs.
Future Trends and Commercial Opportunities
Looking ahead three to five years, three trends are likely to shape where growth and margin opportunities emerge.
Trend 1: Lifecyle-Aware SPDs as a Specification Default
End-of-life visibility, remote indication, and fail-safe disconnection are moving from differentiating features to expected attributes in commercial and industrial applications. As maintenance labor costs rise and downtime becomes more expensive, buyers are likely to favor devices that reduce inspection ambiguity and support planned replacement. The commercial opportunity lies not only in selling hardware, but in aligning product design with maintenance workflows and specification language. Manufacturers that can clearly communicate lifecycle behavior and maintenance readiness may find an advantage in tenders and engineering specs, particularly where facility teams are responsible for large asset bases and limited inspection windows.
Trend 2: Integration into Distribution, Switchgear, and Automation Ecosystems
SPD adoption is likely to accelerate where protection can be incorporated into equipment that is already being procured for other reasons. Plug-in architectures, narrow-profile modular devices, and panel-aligned designs reduce installation friction and make surge protection easier to bundle into broader infrastructure decisions. This trend creates opportunity for suppliers that can demonstrate compatibility, streamline specification, and reduce labor burden. It also creates a challenge for more standalone offerings, which may face longer specification cycles unless they solve a clearly differentiated application need. The strategic implication is that integration is becoming a growth multiplier, especially in commercial and industrial segments where the value of protection can be tied directly to uptime and equipment protection.
Trend 3: Standards-Driven Product Cycles and Regional Divergence
As standards continue to evolve, product cycles will be shaped less by a single breakthrough and more by recurring compliance updates, test coverage, and documentation rigor. Companies that can manage certification agility and keep pace with evolving requirements will be better positioned to maintain market access across regions. At the same time, regional differences in code adoption, installation practice, and preferred product formats will continue to create uneven opportunity sets. In some markets, residential and small-commercial growth may remain constrained by labor cost and price sensitivity, while industrial and larger commercial deployments continue to expand at a steadier pace. The opportunity here is to treat standards and regional requirements as a design input rather than an afterthought, especially for manufacturers with global ambitions or multi-market portfolios.
Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Persistent raw material and energy cost pressure could keep upward pressure on pricing, potentially slowing adoption of premium devices in cost-sensitive segments. Labor availability and installation cost may continue to constrain residential and small-commercial uptake, especially where whole-house solutions require professional installation. Standards evolution can also create transitional friction, as products are updated, re-tested, or repositioned to meet revised requirements. Finally, the market's moderate concentration means competitive dynamics can shift if regional players gain traction through service, pricing, or localized specification relationships. These risks do not undermine the growth outlook, but they do suggest that execution quality around compliance, integration, and cost communication will matter as much as product performance.
Implications for Decision Makers
The SPD market is no longer just a story about surge current ratings and basic certification. It is increasingly a story about how protection is specified, installed, maintained, and integrated into broader infrastructure. That shift creates different implications for different roles.
For Manufacturers
Differentiate through integration and lifecycle visibility rather than hardware specifications alone. Devices that fit naturally into established panel, switchgear, or automation ecosystems, and that provide clear status feedback or fail-safe behavior, are better positioned for specification in commercial and industrial environments. Equally important is certification readiness and documentation discipline, since evolving standards can influence both market access and buyer confidence. Manufacturers should also consider how installation labor and maintenance effort affect total cost perception, because reducing friction at deployment and inspection can be as valuable as improving surge-handling performance. Where possible, targeting high-value niches such as signal-level protection, hazardous-area environments, or narrow-profile modular formats can create stronger margins and more defensible positioning.
For Investors
Focus on business models and product strategies that benefit from recurring specification pull rather than one-off hardware sales. Value is likely to accrue to companies that can align with integration points, demonstrate compliance agility, and communicate total-cost advantages in downtime-sensitive segments. The market's moderate concentration suggests that scale alone does not guarantee outsized share gains; differentiation through application fit, lifecycle design, and specification alignment may be more durable. Investors should also watch how standards updates affect product roadmaps and regional access, because compliance execution can become a competitive differentiator or a launch bottleneck depending on the company's readiness.
PW Consulting
For Procurement and Specification Teams
Move the evaluation conversation beyond upfront price and basic ratings. Include installation labor, maintenance visibility, replacement simplicity, and compliance documentation in the selection criteria, because these factors increasingly determine real-world total cost and operational risk. Where possible, favor devices that integrate with existing distribution or panel platforms, and verify that end-of-life signaling or status indication aligns with your maintenance processes. In commercial and industrial contexts, specify for lifecycle behavior and downtime avoidance as much as for surge handling, since the clearest value often comes from reducing inspection uncertainty and planned replacement friction. In residential or small-commercial settings, weigh installation complexity and labor cost carefully, because these can be the main barriers to adoption even when the protection rationale is sound.
Surge Arresters Market
Strategic Intelligence as a Decision Multiplier
The SPD market is moving through a period in which growth is real, but value capture is uneven. Companies that treat surge protection as an integrated, lifecycle-aware, and standards-aligned part of infrastructure planning are better positioned to win specification, reduce installation and maintenance friction, and build credibility with buyers who are increasingly focused on uptime and operational resilience. For organizations making build, buy, partner, or specification decisions, the most useful intelligence is granular: it connects regional requirements, product formats, end-use dynamics, and competitive moves to the specific segments where a strategy will actually be tested. Detailed segmentation data, competitive profiling, and scenario analysis can help turn broad market direction into concrete commercial choices. For readers seeking a deeper dive into subsegment breakdowns, regional nuances, and customized strategic implications, the full PW Consulting market research report provides the structured detail needed to support planning and execution at the segment level.
For detailed analysis of this topic, please visit the official page: Surge Protection Device (SPD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Isononanoic Acid Market: Why the 5.2% CAGR to $318M by 2032 Changes Everything
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Isononanoic Acid Market
The isononanoic acid market is entering a period of structural transformation where traditional supply chain assumptions no longer hold and value capture is shifting toward companies that can align feedstock strategy, regulatory compliance, and application advantage. Valued at approximately 175.0 million USD in 2020, the market expanded to roughly 220.0 million USD by 2025, and forward indicators point to a trajectory of 318.0 million USD by 2032. This progression corresponds to a compound annual growth rate of 5.2 percent, but the meaning of that growth lies less in the headline number than in the composition of demand, the geography of consumption, and the pricing power embedded in specialized grades. For executives and investors, the central question is not whether the market will expand, but where margins will be earned and which capabilities will allow firms to participate safely in a more volatile, regulation-driven environment.
The wide base of consumption across plastics, lubricants, coatings, metalworking fluids, and specialty intermediates means that isononoic acid benefits from diversified end-use pull. However, this diversification also creates uneven exposure to macro cycles. Linear and branched variants serve different performance profiles and price sensitivity levels, while regional consumption patterns reflect both industrial maturity and local regulatory pace. At the current stage, the market is neither a commodity slugfest nor a niche specialty segment; it is a performance chemical space where feedstock access, grade purity, and formulation partnerships determine which players can convert volume growth into durable profitability.
Market Snapshot
The historical arc from 2020 through 2025 shows steady expansion with a notable mid-cycle adjustment in 2024 before a rebound in 2025. That pattern is consistent with a market absorbing raw material swings, inventory recalibrations, and shifting demand mix across industrial customers. Looking ahead, the forecast window to 2032 suggests continued expansion, with the largest absolute gains accumulating toward the late part of the period as replacement demand matures and new formulations in lubricants and polymer systems reach broader adoption.
What matters strategically is that the growth path is not uniform across applications or regions. Demand is being shaped by substitution away from legacy environments, the performance requirements of engineered fluids, and the ongoing push toward lower-emission formulations. Companies that can translate these shifts into captive grade development, reliable logistics, and application-specific technical service are positioned to earn a premium relative to pure volume players.
Core Challenges and Inflection Points
The first inflection point is regulatory substitution. Legacy phthalates have been drawn into heightened scrutiny under frameworks such as EU REACH, accelerating the use of non-phthalate alternatives in flexible PVC compounding and lubricants. Isononanoic acid-based chemistry is benefiting from this structural shift, but substitution is not instantaneous. Formulators must qualify new systems, manage performance trade-offs, and secure supply consistency. For producers, the opportunity is real but dependent on technical support and qualification timelines rather than simple price competition.
Worldwide Isononanoyl Chloride Market
The second inflection point is feedstock and pricing volatility. Isononanoic acid production relies on C9 alcohol intermediates derived from propylene oligomerization or Fischer-Tropsch feedstocks, and volatility in n-butene and propylene prices directly affects supply chains. Upstream C5 hydrocarbon isopentane prices have held relatively steady in select regional markets as of April 2025, but that stability is not guaranteed to persist across all geographies or time horizons. The result is a market where cost structures are sensitive to both petrochemical cycles and localized supply conditions. Businesses that rely on spot procurement without hedging strategy or long-term alignment are exposed to margin erosion during transition periods.
The third inflection point is the regulatory push on blowing agents and emissions. Mandates around high-GWP hydrofluorocarbon blowing agents are driving migration toward hydrocarbon-based isopentane co-feedstocks for downstream ester production, while low-VOC directives in Europe and analogous North American regulations are accelerating demand for lower-emission alkyd resins and coatings that incorporate isononanoic acid monomers. Together, these dynamics are reshaping end-use priorities and rewarding producers and distributors who can provide compliant grades and formulation support. The challenge is execution: compliance is not only a documentation exercise but a product development and supply assurance commitment.
Key Drivers Shaping the Market
Technical Innovation Across Grades and Applications
Differentiation in this market increasingly depends on grade design and application fit. Linear forms remain central where consistent performance and broader compatibility are required, while branched variants address specific rheological, solvency, or stability needs. High-purity grades have become especially relevant for refrigeration lubricants and engineered fluids, where impurity control affects system reliability and service life. Producers investing in specialized carboxylic acid portfolios and dedicated capacity for performance grades are better positioned to serve customers that require consistent specifications and repeatable batches rather than standard commodity output.
Innovation is also showing up in how grades are integrated into downstream systems. In lubricant applications, isononoic acid supports polyol ester synthetic lubricants and functional fluids that demand thermal stability and compatibility with advanced base stocks. In coatings and alkyd systems, the monomer's role in low-emission formulations aligns with regulatory momentum and customer preference for reduced VOC profiles. The commercial implication is that technical service, grade selection guidance, and application testing are becoming value drivers alongside volume supply.
PW Consulting Chemical & Energy Research Center
Policy and Regulatory Environment as a Structural Tailwind
Regulation is no longer a peripheral risk factor; it is a central driver of substitution and product design. EU REACH's classification of legacy phthalates as substances of very high concern has accelerated replacement by isononanoic acid-based alternatives in flexible PVC and lubricants. Parallel developments in the United States and other jurisdictions have mandated the phase-out of high-GWP blowing agents, encouraging migration to hydrocarbon-based co-feedstocks that tie into downstream ester chemistry. European VOC directives and North American low-VOC requirements are further expanding demand for low-emission alkyd resins and coatings that incorporate isononoic acid monomers.
In parallel, sustainability certification is influencing procurement choices. ISCC PLUS requirements for bio-based content are encouraging manufacturers to invest in circular and bio-based pathways within carboxylic acid supply chains. This is not a short-lived trend; it reflects a wider shift toward verifiable feedstock provenance and reduced lifecycle impact. Companies that can supply certified content or document circularity attributes are likely to gain preference in customer qualification processes, particularly where brand owners and OEMs face their own sustainability commitments.
Isononyl Alcohol Market
Demand-Side Shifts in Lubricants, Coatings, and Engineered Fluids
On the demand side, the most consequential change is the redefinition of performance expectations across multiple end-use categories. Synthetic lubricants and refrigeration lubricants require fluids that maintain stability under demanding operating conditions, and high-purity isononoic acid is a building block in those systems. At the same time, coatings formulators are under pressure to reduce emissions without sacrificing durability or application performance, which creates demand for monomers and intermediates that support lower-VOC architectures. In personal care intermediates and metalworking fluids, the value is more application-specific, but it is still shaped by the same themes: regulatory compliance, performance consistency, and supply reliability.
These demand-side changes reward suppliers that can act as formulation partners rather than passive distributors. When end users are adapting to new regulatory constraints and performance targets, they look for suppliers who can provide sample support, specification guidance, and dependable delivery. This dynamic strengthens the position of firms with technical capability and application focus, particularly in regions where industrial customers are undergoing rapid reformulation.
Supply Chain and Cost Structure Realignment
Feedstock linkage to propylene and n-butene markets means that isononoic acid supply chains are exposed to upstream price swings. Recent dynamics underscore the sensitivity of cost structures to both commodity movements and geopolitical disruption. Following the Middle East conflict, Perstorp Oxo AB implemented a global price increase effective March 1, 2026, citing sharply increasing raw material and energy prices, and then implemented a further increase effective April 1, 2026, reflecting supply and demand balance changes. These steps illustrate how quickly cost conditions can shift and how pricing power is being reasserted in a tight environment.
At the same time, regional feedstock conditions are not identical. The relative steadiness of isopentane pricing in certain Chinese markets as of April 2025 suggests that local balances can diverge from broader petrochemical trends. For procurement and planning teams, the lesson is that regional sourcing logic, inventory strategy, and contractual flexibility matter more than generic assumptions about cost trends. Businesses that build multi-source options and anticipate lead-time variability are better placed to manage volatility without sacrificing service levels.
Competitive Landscape and Leading Strategies
Incumbent Producers and Differentiated Positioning
BASF SE operates a global carboxylic acids portfolio with production footprint including Germany and Malaysia, supporting applications such as polyol ester synthetic lubricants, paint dryers, and metal salts. Its advantage lies in scale, portfolio breadth, and the ability to serve multiple downstream markets with integrated chemical capabilities. For customers seeking broad availability and a supplier with strong application reach, BASF represents a strategic anchor in the value chain.
OXEA GmbH is a dedicated manufacturer of isononoic acid and related grades, with focus on synthetic lubricants, corrosion inhibitors, functional fluids, and polymer stabilizers. This specialization supports consistent grade control and application alignment, which is valuable where formulators need repeatable purity and specification stability. In a market where performance differentiation increasingly matters, dedicated producers can command stronger commercial positioning by offering predictable quality and focused technical support.
Perstorp Oxo AB supplies isononoic acid for refrigeration lubricants and engineered fluids, with emphasis on high-purity grades and complete building block portfolios. Its positioning is particularly relevant where thermal stability and purity requirements are stringent. The recent pricing actions taken in 2026 reflect not only cost pressure but also the strategic use of pricing to manage supply-demand balance in a constrained environment. This approach underscores the importance of proactive supply planning for customers reliant on high-purity inputs.
KH Neochem Co., Ltd. provides isononoic acid under the KYOWANOIC-N trade name, with industrial applications spanning lubricants, coatings, and personal care intermediates. Its role illustrates the importance of branded, application-anchored supply in markets where buyers value traceability and consistent quality. Neuchem, as a North American distributor and supplier with long-standing exclusive supplier relationships, supports lubricants, metalworking fluids, and chemical processing through flexible packaging options ranging from drums to bulk. Its model shows how distribution depth and logistics flexibility can create value in regional markets where service reliability is as important as product availability.
Univar Solutions and Parchem Fine & Specialty Chemicals operate as active distributors of technical-grade material for synthetic lubricants, corrosion inhibitors, alkyd resins, and coatings. Their presence broadens access to isononoic acid across multiple applications and geographies, but it also highlights a structural reality in the market: distribution capability and application knowledge can be as important as production scale. For many buyers, the choice of channel depends on required grade, lead time, technical support, and the ability to integrate supply into broader formulation workflows.
Market Structure and Evolving Dynamics
Concentration remains moderate, with a significant share held by a limited number of leading producers and distributors. This creates a landscape where scale and portfolio depth matter, but where specialization, grade control, and regional service also determine commercial success. The market is not consolidating into a single dominance pattern; rather, it is evolving into a segmented structure in which different players lead in different application niches and geographies.
Several forces are likely to shape the next phase of competitive dynamics. First, the continued push toward certified and renewable feedstocks may favor producers that can document sustainability attributes and secure bio-based or circular inputs. Second, regulatory substitution will elevate the importance of application-specific grades, benefiting firms that can support qualification and scale-up with customers. Third, volatility in feedstocks and energy will test the resilience of cost structures, rewarding those with flexible procurement strategies and strong supplier relationships. In this environment, new entrants will find the greatest traction where they can credibly address a specific application need or regional service gap rather than compete broadly on price alone.
Future Trends and Commercial Opportunities
Acceleration of Non-Phthalate and Low-Emission Formulations
Over the next three to five years, substitution trends are likely to deepen as regulatory frameworks mature and end-user qualification cycles advance. The movement away from legacy phthalates and toward lower-VOC coatings and alkyd resins supports ongoing demand for isononoic acid-based building blocks. The commercial opportunity lies in capturing formulation partnerships early, offering grade options that meet evolving requirements, and providing documentation that simplifies customer compliance. Producers and distributors that invest in technical service and qualification support will be better positioned to convert regulatory momentum into repeat business.
The related risk is that substitution speed can vary by sector and geography. In some markets, legacy systems persist due to cost constraints, performance concerns, or slow qualification. Businesses should therefore plan for a phased transition rather than assuming immediate adoption across all applications.
Feedstock Strategy and Pricing Discipline as Margin Defenders
Given the dependence on propylene-related intermediates and the demonstrated exposure to energy and raw material shocks, feedstock strategy will remain central to profitability. Companies that secure reliable intermediate supply, maintain contractual flexibility, and align inventory policy with demand variability will be better able to protect margins during volatile periods. The recent pricing actions in early 2026 also suggest that pricing discipline can be exercised when supply-demand balance tightens, but only if customers perceive risk and reliability as worth paying for.
The opportunity here is twofold. For producers, stronger feedstock alignment and cost discipline can support better margin control and more predictable commercial terms. For buyers, diversifying sources and planning for lead-time variability can reduce exposure to abrupt price changes and availability disruptions. The risk is that any over-reliance on single-source supply or rigid procurement models increases vulnerability to upstream shocks.
Growth Concentrated in Specialized Grades and Certified Content
Expansion to 2032 is likely to be supported not by uniform volume growth across all forms, but by concentration in higher-value grades and applications where performance and compliance create willingness to pay. High-purity grades for refrigeration and engineered fluids, non-phthalate alternatives for flexible PVC and lubricants, and low-emission coating inputs all represent areas where value addition can outpace commodity inflation. In parallel, demand for verified bio-based or circular content may increasingly influence procurement decisions, particularly where downstream brands require sustainability documentation.
The strategic opportunity is to align product development and supply assurance with these premium segments. Businesses that can deliver consistent purity, certification readiness, and application support will be more resilient to price competition in commodity segments. The uncertainty lies in the pace of certification adoption and the degree to which sustainability attributes translate into purchasing preference across all regions and customer segments.
Actionable Guidance for Decision-Makers
For Manufacturers and Formulators
Prioritize grade selection based on application performance and regulatory fit rather than treating isononoic acid as a generic input. Where reformulation is underway, invest in early technical engagement with suppliers to reduce qualification time and avoid performance surprises. Build supply arrangements that combine reliability with flexibility, and consider multi-source strategies where feedstock or logistics risk is elevated. If sustainability documentation is increasingly required by your customers, evaluate sourcing options that support certification or traceability claims without disrupting production continuity.
For Investors
Focus on the segments where premiumization and substitution are most evident: high-purity engineered fluid inputs, non-phthalate replacements, and low-emission coating-related monomers. Evaluate companies and supply chains based on feedstock resilience, grade differentiation, and the ability to support customer qualification. Be attentive to the implications of regional feedstock volatility and energy cost exposure, since these factors can affect margin stability even when demand trends are favorable. Where possible, favor businesses with demonstrated technical service capability, as that capability often underpins pricing power in performance chemical markets.
For Procurement and Supply Chain Leaders
Treat feedstock-linked volatility as a planning variable rather than an exceptional event. Incorporate lead-time variability, regional pricing divergence, and regulatory-driven demand shifts into inventory and contract strategy. Where dependence on high-purity or certified grades is significant, secure visibility into supplier capacity, packaging options, and documentation processes. A diversified sourcing approach, combined with clear specification requirements and service-level expectations, can reduce the operational impact of market disruptions while maintaining access to the grades most relevant to your applications.
The strategic value of timely, granular intelligence in this market lies in understanding how substitution pace, feedstock conditions, and regional regulation interact to shape both opportunity and risk. Detailed segmentation data, regional pricing dynamics, and application-specific demand shifts can materially improve planning accuracy and commercial execution. For decision-makers seeking deeper insight into market size breakdowns, regional trajectories, and customized recommendations aligned to specific business models, the complete PW Consulting research report offers expanded coverage and tailored analysis to support more precise strategic choices.
For detailed analysis of this topic, please visit the official page: Isononanoic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tire Changers Market 2026: Why 6.8% CAGR and Asia Pacific’s Scale Shift Everything
By PW Consulting, 2026-09-21
Beyond the Service Bay: Strategic Shifts Reshaping the Tire Changers Market Through 2032
Market Trajectory: From Incremental Growth to Structural Expansion
The global tire changers market is undergoing a transformation that extends well beyond routine equipment replacement cycles. Valued at approximately 1,471 million USD in 2025, the market has expanded at a steady pace since 2020, when it stood near 1,135 million USD. This growth reflects not only broader automotive service activity but also a fundamental shift in how service centers, fleets, and independent shops approach wheel maintenance efficiency, safety compliance, and operational throughput.
Projecting forward through 2032, the market is expected to surpass 2,300 million USD, supported by a compound annual growth rate of 6.8 percent. The trajectory suggests a market that is maturing but still possesses meaningful expansion headroom, particularly as regional service infrastructure develops, vehicle fleets age, and new equipment configurations address increasingly complex rim and tire profiles. The growth is not uniform across all segments, however, and the divergence in adoption patterns points to strategic opportunities for players who can align product capabilities with evolving service demands.
Worldwide Tool Changers Market
Core Challenges at the Inflection Point
Several interconnected challenges are redefining how tire changer manufacturers, distributors, and end users navigate the market. These are not temporary friction points but structural shifts that will influence equipment selection, pricing dynamics, and competitive positioning for years to come.
First, tightening safety and operational compliance requirements are reshaping procurement criteria. Vehicle maintenance environments, particularly those supporting commercial fleets and heavy-duty operations, face heightened expectations around machine guarding, turntable accessibility, and workstation hazard mitigation. Industry guidance continues to emphasize that equipment must meet or exceed established safety standards to reduce compliance exposure and minimize unplanned downtime. For service operators, this elevates the importance of equipment that integrates protective design features without compromising speed or ease of use.
Second, shifting trade policies and import exposure are introducing volatility into equipment sourcing and cost structures. Recent policy movements have placed renewed attention on the origin of automotive service equipment, affecting pricing assumptions and supply continuity for buyers who rely on cross-border procurement. The change is prompting service businesses and manufacturers alike to reassess supply chain dependencies, localize component sourcing where feasible, and evaluate total cost of ownership rather than upfront price alone.
Third, the evolving tire and wheel landscape is placing new technical demands on change equipment. As service centers encounter wider variety in rim diameters, lower-profile tires, and mixed passenger and commercial workloads within the same bay, equipment that once performed adequately for generalized use is increasingly expected to handle more specialized applications. This is driving interest in flexible mount configurations, enhanced bead-breaking performance, and designs that reduce manual force requirements while maintaining operator control.
Key Drivers Accelerating Market Evolution
Technology Innovation and Equipment Differentiation
Innovation in tire changer design is moving beyond incremental feature additions toward more integrated, ergonomic, and application-specific solutions. A clear trend is the development of hybrid mount systems that blend the speed and consistency of automatic or semi-automatic operation with the adaptability of leverless or swing-arm configurations. These systems address a practical service center challenge: reducing changeover time while limiting tire and rim damage risk on challenging assemblies.
PW Consulting
Recent equipment introductions highlight this direction. One major engineering provider expanded its table-top and center-clamp offerings with models featuring hybrid leverless mount heads, enhanced torque capabilities, and integrated inflation systems designed to streamline the full change cycle. Additional center-clamp and swing-arm combinations have focused on merging the advantages of both configurations, giving operators more flexibility when working with difficult bead seats or non-standard rim geometries. In parallel, other manufacturers have refreshed product platforms with emphasis on shop efficiency, stronger jaw configurations for commercial wheel sizes, and simplified controls that support faster operator training.
The practical implication is that equipment performance is increasingly being measured by repeatability, operator safety, and the ability to handle a broader range of tire and wheel profiles without frequent re-tooling or manual intervention. For manufacturers, this creates a competitive environment where differentiation stems less from basic functionality and more from how well the equipment fits specific shop workflows.
Regulatory and Safety Standards as a Market Shaping Force
Regulatory expectations are becoming a more prominent element of equipment selection and procurement strategy. Safety guidelines relating to machine guarding, turntable edge protection, and workstation hazard control continue to influence how service centers evaluate tire changers, especially in commercial and fleet maintenance environments. Equipment that supports compliance through integrated guarding, clear operational zones, and reduced exposure to pinch or trip hazards is gaining preference in risk-conscious buying environments.
This regulatory emphasis interacts with operational realities in fleet service. Out-of-service criteria and downtime sensitivity make reliability and consistency important procurement considerations, not only from a safety standpoint but also from a logistics perspective. When maintenance interruptions carry consequences for fleet availability, equipment that supports predictable cycle times and reduces manual variability becomes more valuable. In this context, regulatory alignment is not simply a compliance checkbox; it is increasingly part of a broader operational resilience discussion.
Demand-Side Shifts in Service Behavior
Service behavior is shifting on both the passenger and commercial sides, though for different reasons. Passenger vehicle service demand continues to benefit from growing vehicle parc activity, seasonal tire change programs, and a broader emphasis on preventive maintenance. At the same time, commercial vehicle service demand is being shaped by fleet maintenance requirements, uptime pressures, and the need to service larger and sometimes mixed wheel configurations efficiently.
These demand patterns are influencing the relative attractiveness of different equipment categories. Shops handling higher passenger vehicle volumes tend to prioritize fast change cycles, consistent mounting performance, and space-efficient equipment footprints. Commercial-focused operators place greater weight on robustness, bead-breaking capability, and compatibility with heavier or larger-diameter wheels. As service centers increasingly manage blended workloads, demand is rising for equipment that can adapt across these contexts without forcing separate line investments for each application type.
Cost Structure and Supply Chain Realignment
Cost dynamics are being reshaped by both input material considerations and broader sourcing strategy changes. Equipment that relies heavily on durable structural materials such as steel for frames and load-bearing components presents a different cost and longevity profile than lighter or fully imported alternatives. In an environment where procurement teams are more attentive to lifecycle durability, serviceability, and supply continuity, the emphasis is shifting toward equipment that offers predictable maintenance demands and resistance to premature wear.
At the same time, sourcing complexity is encouraging manufacturers and distributors to think more strategically about regional production footprints, component availability, and the balance between import dependency and localized assembly or fabrication. For buyers, this translates into greater scrutiny of supplier reliability, spare parts access, and the longer-term economic implications of equipment selection beyond the initial purchase price.
Competitive Landscape: Positioning, Differentiation, and Structural Change
The tire changers market features a mix of established manufacturers with strong regional presence, specialized equipment providers, and firms leveraging broader automotive service portfolios. Competitive advantage is increasingly defined by product versatility, workflow integration, and the ability to support compliance and durability expectations while maintaining effective pricing and service support.
One U.S.-based engineering company has continued to consolidate attention around its tire changer line by introducing multiple product updates within a short period. Its recent launches have emphasized hybrid leverless mount heads, enhanced torque delivery, integrated inflation systems, and lower locking disc configurations. These updates illustrate a strategy centered on expanding the capability range of core platforms while addressing difficult tire and rim combinations that can slow traditional change processes. By positioning its products as adaptable across table-top, center-clamp, and swing-arm use cases, the company is reinforcing a message of workflow flexibility for service centers that need to accommodate varied tire and wheel profiles.
Another U.S. manufacturer has taken a different but complementary approach, emphasizing domestically designed and built equipment with strong structural component choices and feature enhancements aimed at commercial wheel sizes. Recent updates have included stronger jaw options for larger commercial diameters, refreshed shop-facing branding, and product presentations tied to professional service audiences. The emphasis on steel-intensive construction and application-specific jaw configurations signals a focus on durability and commercial service demands, an angle that resonates with buyers concerned about heavy usage cycles and long equipment life.
Additional competitors reflect the breadth of the landscape. Some firms concentrate on car, truck, and motorcycle applications with accessible professional-grade solutions, often pairing tire changers with complementary shop equipment to deliver more complete service bay packages. Others, particularly in Europe, have built reputations around integrated wheel service systems, combining tire changers with balancers and alignment-related equipment to support full-service workflows. Chinese manufacturers have also continued to participate in the market with automatic and touchless-style designs that target efficiency and specialized mounting needs. Italian equipment makers remain notable for superautomatic and standard configurations directed at garages and service centers, while other established suppliers focus on variable-speed direct-drive designs or rim-clamp models tailored to repair shop use.
The overall competitive structure shows moderate concentration, with leading firms holding meaningful share while leaving substantial room for regional specialists and application-focused entrants. This fragmentation is likely to persist in the near term, but the nature of competition is shifting. Rather than competing only on basic equipment capability, manufacturers are increasingly differentiating through product families that span multiple mounting styles, integrated shop-system positioning, and feature sets that respond directly to compliance, durability, and operator efficiency expectations.
Market evolution is also being shaped by the interplay between established players and new product introductions that blur traditional category lines. Hybrid configurations, enhanced commercial wheel compatibility, and integrated shop efficiency features suggest that the boundary between fully automatic, semi-automatic, and manual-oriented equipment is becoming more flexible in practice. Buyers are increasingly evaluating platforms based on the operational outcomes they enable rather than strict equipment classification.
Tire Market
Future Trends Shaping the Next Three to Five Years
Trend One: Convergence Toward Flexible, Application-Responsive Platforms
Over the next several years, demand is likely to continue favoring tire changers that can handle a wider mix of tire and wheel profiles without requiring multiple dedicated machines. Hybrid mount systems, adaptable jaw or duckhead configurations, and designs that support both passenger and light commercial use will become increasingly important in mixed-workload service environments. This trend creates opportunity for manufacturers that can offer scalable platforms and for service centers that can consolidate equipment while expanding service coverage. It also introduces a risk: platforms that promise flexibility but sacrifice reliability, ease of training, or maintenance simplicity may struggle to retain buyer confidence.
Trend Two: Compliance, Safety, and Uptime as Core Purchase Criteria
Safety and regulatory alignment will continue moving from a secondary consideration to a primary procurement driver, especially in commercial fleet service and higher-volume maintenance environments. Equipment selection will increasingly account for guarding design, workstation layout, operator exposure reduction, and consistent cycle performance that supports downtime management. The commercial opportunity lies in products and service packages that frame compliance and uptime as integrated benefits rather than separate features. The uncertainty lies in how standards, inspection practices, and enforcement expectations may further evolve, which could change the relative weight of specific equipment attributes over time.
Trend Three: Regional Sourcing, Cost Discipline, and Lifecycle Value Thinking
As equipment buyers become more attentive to sourcing exposure, long-term durability, and total cost of ownership, market dynamics will favor suppliers that can articulate clear lifecycle value and maintain predictable parts and service support. Domestic or regionally anchored production strategies, durable structural design, and transparent maintenance requirements may gain relative advantage in segments where operational continuity matters most. At the same time, import-dependent supply paths may face continued pressure from policy changes and buyer risk tolerance. The strategic opportunity is for manufacturers and distributors to build clearer value narratives around durability, service access, and supply reliability, while buyers benefit from more disciplined equipment evaluation frameworks.
Strategic Implications for Decision Makers
For manufacturers and product leaders, the near-term priority is to strengthen platform versatility without diluting reliability. Product strategies that combine hybrid mounting options, commercial wheel compatibility, and clear operator-safety design are well positioned to address the converging demands of passenger and commercial service environments. Equally important is the ability to support these products with dependable parts availability, service guidance, and a value proposition that extends beyond initial pricing. Companies that can connect product features to measurable shop outcomes—reduced change time, lower operator fatigue, fewer compatibility limitations, and stronger compliance support—will have a stronger footing in an increasingly outcome-driven buying environment.
For investors and strategic partners, the market offers opportunity in segments where durability, compliance alignment, and mixed-application flexibility are gaining weight. Attention should be directed toward manufacturers with coherent product roadmaps, clear regional or supply-chain positioning, and the ability to serve both specialized and broad-service customers. Investment theses should account for the possibility that trade-policy exposure, raw material dynamics, and shifting procurement preferences may alter competitive advantages over time, making supplier resilience as important as product strength.
For procurement teams and service operators, equipment evaluation should move beyond headline specifications and incorporate workflow fit, safety design, commercial wheel compatibility, and long-term serviceability. The most effective purchasing decisions will increasingly reflect how equipment supports bay productivity, compliance readiness, and the ability to handle a broader mix of tire and wheel service demands without unnecessary specialization overhead. Framed this way, tire changers become not just a maintenance tool but part of a broader operational efficiency and risk management strategy.
Detailed segmentation data, company-level capability mapping, and application-specific demand patterns can materially sharpen these decisions. For organizations seeking a deeper view of regional dynamics, product-category shifts, and competitive positioning across the tire changers market, the full PW Consulting research report provides a more granular foundation for planning and investment prioritization.
For detailed analysis of this topic, please visit the official page: Tire Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oscilloscope Market 2032: How 6.95% CAGR and 72.3% CR3 Reshape Competition
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Oscilloscope Market
The oscilloscope market is undergoing a structural transformation driven by escalating signal complexity, the proliferation of high-speed digital architectures, and a widening gap between traditional benchtop instrumentation and software-defined measurement workflows. As electronic systems push into multi-gigabit bandwidth regimes and real-time diagnostics become embedded in product development cycles, oscilloscopes are evolving from standalone capture devices into integrated analysis platforms. This shift is reshaping demand patterns, competitive positioning, and investment priorities across the test and measurement ecosystem.
Market Overview and Core Challenges
Commercial Trajectory and Structural Dynamics
The global oscilloscope market has demonstrated steady expansion over the past half-decade, with revenue crossing 200 billion dollars in recent years and continuing its upward trajectory into the mid-twenties. The market's compounded annual growth rate of approximately 6.95 percent through the forecast horizon reflects a maturing yet still expanding category, where incremental adoption is increasingly tied to advanced capability upgrades rather than base-level replacement. Revenue distribution across form factors reveals a dominant benchtop foundation, complemented by a rapidly growing portable segment and a substantial PC-based footprint that underscores the industry's pivot toward software-centric workflows. Bandwidth segmentation highlights a concentration of demand in the mid-range spectrum, while the sub-500 MHz tier remains a steady volume driver for general-purpose applications. Higher bandwidth categories, particularly those exceeding 4 GHz, represent a smaller but strategically critical slice tied to high-speed digital design, signal integrity validation, and next-generation communication testing. Industry-level demand spreads across automotive and transportation, IT and telecommunications, consumer electronics, aerospace and defense, medical and life sciences, and a diversified remainder, reflecting the instrument's cross-sector relevance.
The market is characterized by pronounced concentration, with a small group of established players commanding a substantial share of global revenue. This consolidated structure has historically reinforced premium pricing, long product lifecycles, and deep application-specific support. However, the same concentration also creates pressure points as demand fragments across more diverse testing scenarios and price-sensitive segments expand in emerging manufacturing hubs.
Key Challenges and Inflection Points
The industry faces several intertwined challenges that are redefining how manufacturers, buyers, and investors evaluate opportunity. First, the boundary between hardware performance and software capability is blurring. Advanced waveform analysis, automated compliance testing, and AI-assisted interpretation are becoming differentiators that matter as much as raw bandwidth or sampling rate. Companies that continue to compete primarily on analog specifications risk ceding ground to platforms that deliver faster time-to-insight and tighter integration with design environments.
Second, supply chain and component availability for high-performance analog front-ends, precision clocks, and high-speed digitizers remain sensitive to geopolitical and semiconductor cycle dynamics. Leading manufacturers are navigating longer validation cycles and elevated lead times for critical subsystems, which affects time-to-market for next-generation series and complicates capacity planning in high-growth regions.
Third, the purchasing behavior of engineering teams is shifting. Design organizations increasingly favor instruments that support bench-to-field workflows, remote collaboration, and seamless data export into simulation and verification tools. This demand-side evolution is pressuring incumbents to rethink channel strategies, service models, and the balance between entry-level volume products and high-margin specialized systems.
Key Demand Drivers
Technology Innovation and Capability Gaps
The most consequential driver is the accelerating pace of signal complexity in modern electronic architectures. High-speed serial links, advanced packaging, RF-intensive designs, and mixed-signal integration are pushing test requirements beyond traditional capture capabilities. In this environment, oscilloscopes are being asked to deliver higher waveform capture rates, deeper memory, lower noise floors, and more sophisticated analysis libraries. The recent emphasis on real-time instruments tailored for high-speed digital and compliance testing illustrates how vendors are aligning product roadmaps with these technical demands. Simultaneously, the introduction of compact mixed-signal platforms designed for seamless bench-to-field workflows signals a broader push toward portability, multi-channel flexibility, and field-deployable diagnostics without sacrificing analytical depth.
A second technology-related driver is the integration of intelligent analysis features. Automation of measurements, pattern recognition, and guided troubleshooting are reducing the dependency on highly specialized operators and enabling faster iteration in development cycles. This trend is particularly relevant for teams working on 5G-related validation, quantum computing instrumentation, and advanced signal integrity applications, where the volume and complexity of captured data make manual interpretation impractical.
PW Consulting
Policy and Regulatory Environment
Regulatory and compliance requirements are shaping demand in subtle but persistent ways. Automotive safety standards, emissions testing mandates, and industry-specific certification frameworks are expanding the scope of required validation, especially in sectors where electronic control units, power Electronics, and communication modules must meet rigorous performance thresholds. In aerospace and defense, traceability, measurement confidence, and long-term supportability continue to favor established instrumentation with documented calibration and verification pathways. These requirements create a steady baseline of demand for compliant, well-supported platforms, while also raising the barrier for new entrants that lack institutional credibility or comprehensive service networks.
Demand-Side Shifts in Engineering and Manufacturing
Engineering organizations are under increasing pressure to shorten design cycles and reduce rework. The adoption of mixed-signal architectures, broader use of embedded sensors, and tighter integration between hardware and software teams are driving demand for instruments that can support multiple use cases without requiring separate toolchains. Portable and PC-based formats are gaining relevance in environments where measurements must be taken outside traditional lab settings, including field commissioning, production line debugging, and remote diagnostics. At the same time, larger enterprises are prioritizing platforms that connect to enterprise data workflows, enabling measurement results to feed directly into quality systems, design reviews, and compliance documentation.
Supply Chain and Cost Structure Evolution
Cost dynamics are increasingly influenced by the balance between performance differentiation and affordability. In entry-level and mid-range segments, competitive pressure is intensifying as manufacturers expand feature sets that were once reserved for higher tiers. This compression is prompting a recalibration of pricing strategies and encouraging a segmentation approach in which value is created through application-specific bundles, software subscriptions, and support services rather than hardware alone. On the supply side, the need for high-quality analog components and precision fabrication continues to favor scaled manufacturers with strong procurement relationships and multi-sourced component strategies. Companies that can maintain stable production while introducing differentiated analysis capabilities are better positioned to protect margins in a more crowded competitive field.
Competitive Landscape and Leading Strategies
Strategic Positioning of Core Players
The competitive environment is shaped by a mix of established multinational manufacturers and focused regional players, each pursuing distinct value propositions. One U.S.-based leader has built a strong identity around high-performance oscilloscopes for high-speed digital, 5G, and quantum computing applications, reinforced by AI-assisted analysis capabilities. Its recent launch of a real-time oscilloscope series targeting high-speed digital and compliance testing demonstrates a strategy centered on pushing the performance envelope while embedding smarter interpretation tools. The emphasis on advanced compliance workflows indicates a deliberate move toward use cases where measurement accuracy, repeatability, and regulatory alignment carry substantial commercial weight.
A second U.S. incumbent is widely recognized for digital phosphor and mixed-signal oscilloscopes that extend into high-frequency ranges with advanced waveform analysis. Its introduction of a mixed-signal oscilloscope designed for bench-to-field workflows reflects an effort to bridge laboratory precision with field usability, a positioning that appeals to engineering teams seeking continuity across development, validation, and deployment environments. This approach underscores a broader strategic theme: reducing friction in measurement workflows rather than competing solely on specification sheets.
A German manufacturer has carved out a strong position with compact and entry-level oscilloscopes offering multiple channels and high waveform capture rates, particularly in general and automotive testing. Its focus on accessible multi-channel configurations suggests a strategy aimed at capturing volume in sectors where testing throughput and channel density are critical, while still maintaining a credible presence in performance-oriented applications. A U.S. specialist remains closely associated with high-bandwidth sampling oscilloscopes for signal integrity and high-speed testing, a niche that rewards deep domain expertise and application-specific optimization. A Japanese measurement company continues to emphasize precision test and measurement oscilloscopes for industrial and engineering applications, leveraging a reputation for reliability and long-tail support.
On the other side of the competitive spectrum, Chinese manufacturers are expanding their footprint in affordable digital oscilloscopes for bench and educational use, as well as high-resolution instruments for high-speed signal integrity testing. Their growth is closely tied to price competitiveness, feature densification at lower price points, and growing acceptance in cost-sensitive markets and training environments. A UK-based provider has focused on USB-based oscilloscopes for portable and PC-integrated signal capture, an approach that aligns with the broaderPC-based and portable momentum and serves users who prioritize integration simplicity and flexibility over standalone instrument form factors.
Market Evolution and Competitive Dynamics
Several structural dynamics are influencing how the competitive landscape is evolving. One is the tension between consolidation and segmentation. While the market remains concentrated at the top, demand is fragmenting across more application-specific requirements, form factors, and price points. This creates space for both specialized leaders and agile challengers, depending on the segment. High-performance and compliance-driven segments tend to reward established credibility and deep support ecosystems, while entry-level and mid-range segments are more contested and sensitive to feature-to-price ratios.
Multimeters Market
Another dynamic is the growing importance of software and services as sources of differentiation. As measurement workflows become more connected and analysis more automated, the value of an instrument increasingly depends on how well it fits into the broader engineering environment. Product launches that emphasize workflow continuity, advanced capture rates, and intelligent analysis suggest that leading manufacturers recognize software-defined value as a durable competitive advantage. At the same time, new entrants and regional players are using affordability and targeted feature sets to gain traction, particularly where procurement budgets and training needs prioritize accessible, versatile tools.
A third dynamic is geographic diversification of demand and supply. While mature markets continue to anchor high-value deployments, growth in Asia Pacific and other developing regions is expanding the addressable base for both premium and cost-effective instruments. This geographic spread is encouraging manufacturers to adapt product portfolios, service coverage, and channel strategies to local engineering practices and procurement norms.
Future Outlook for 2026–2032
Trend 1: Software-Defined Measurement and Intelligent Analysis Become Table Stakes
Over the next several years, the differentiator set for oscilloscopes will increasingly favor platforms that combine strong hardware foundations with software capabilities that accelerate interpretation and decision-making. AI-assisted analysis, automated compliance routines, and deeper integration with simulation, documentation, and quality systems are likely to become more standard across mid-range and high-end offerings. This trend opens commercial opportunities for vendors that can package analysis workflows as repeatable, auditable processes, and for buyers who can reduce engineering cycle time through better measurement-to-insight pathways. The risk is that software expectations rise faster than hardware roadmaps, creating mismatch risk for products that advertise intelligence without corresponding workflow maturity or data interoperability.
Trend 2: High-Speed Digital, Signal Integrity, and Compliance-Driven Demand Will Keep Pulling the High-End Forward
Demand for higher bandwidth, deeper capture, and more precise signal integrity validation is expected to remain a primary engine of premium segment growth. Applications in high-speed digital design, advanced communication testing, and specialized research environments will continue to reward instruments that can handle complex waveforms with low noise and high repeatability. Commercial opportunity here lies in bundled solutions that pair high-performance hardware with application-specific libraries, calibration support, and compliance-oriented documentation. The uncertainty is that the high-end pipeline is sensitive to component availability and validation timelines, which can cause uneven release cadences and temporary gaps between market demand and available capacity.
Trend 3: Form Factor Diversification Will Broaden the Addressable Use Case Set
Portable and PC-based oscilloscope formats are likely to continue gaining relevance as measurement moves beyond the lab and into field, production, and remote settings. Benchtop systems will remain central for high-performance and complex multi-channel work, but the broader market will increasingly value instruments that adapt to varied environments without sacrificing analytical rigor. This creates opportunities for manufacturers that can deliver flexible channel configurations, robust portability, and easy integration with PCs and enterprise tools. The risk is that form factor proliferation complicates product management and service coverage, especially for organizations trying to serve both centralized labs and distributed engineering teams with a unified portfolio.
Dermatoscope Market
Strategic Implications for Decision Makers
For Manufacturers and Product Leaders
Balancing performance leadership with workflow usability will be essential. Investing in analysis software, automated measurement packages, and seamless data export can strengthen stickiness and justify premium positioning, especially in high-speed digital, compliance, and signal integrity markets. At the same time, manufacturers should monitor the entry-level and mid-range segments closely, where feature densification and competitive pricing are reshaping buyer expectations. A clear segmentation strategy, supported by disciplined component sourcing and predictable release cycles, can help protect margins while preserving access to growth regions and application verticals.
For Investors and Strategic Allocators
The most durable value creation in this market is likely to come from businesses that combine credible hardware performance with software-enabled differentiation and strong service ecosystems. Investors should pay attention to product launch cadences that demonstrate alignment with high-growth use cases, as well as to the ability of incumbents and challengers to sustain margin discipline amid rising software expectations and supply chain sensitivity. Companies that can expand recurring value through software, support, and application bundles may offer more resilient growth profiles than those relying primarily on hardware replacement cycles.
For Procurement and Engineering Leaders
Buying decisions should increasingly reflect total measurement workflow value rather than headline specifications alone. Priorities may include waveform capture rates, analysis automation, multi-channel flexibility, portability where field use matters, and integration with existing design and quality systems. Procurement teams should also evaluate long-term supportability, calibration pathways, and the availability of application-specific guidance, particularly in regulated or high-stakes environments. For organizations operating across multiple sites or engineering contexts, instruments that support consistent workflows from bench to field can reduce training overhead and improve measurement continuity.
Closing Perspective
The oscilloscope market is moving from a specification-centric competition model toward a workflow- and analysis-centric one. Growth is being shaped by higher signal complexity, expanding compliance demands, and the need for measurement tools that fit into broader engineering environments rather than standing apart from them. The commercial opportunity lies in aligning product strategy with these realities: delivering high-performance capability where it matters, embedding intelligent analysis where it accelerates decisions, and offering flexible form factors where measurement must travel beyond the lab. For organizations seeking to navigate this landscape with greater precision, a deeper dive into segment-level demand patterns, regional procurement shifts, and competitive release roadmaps can provide the granularity needed to de-risk planning and prioritize the most valuable opportunities.
For detailed analysis of this topic, please visit the official page: Oscilloscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rupture Disc Market: Why the 3.7% CAGR Trajectory Signals Strategic Shifts for 2026
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Rupture Disc Market
Navigating a Mature but Evolving Safety-Critical Segment
The global rupture disc market reflects the steady, requirement-driven nature of pressure relief equipment across process industries. Measured against a 2025 base year and projected through 2032, the market demonstrates a composite annual growth rate of 3.7%, expanding from an estimated 678.2 million USD in 2025 to 874.6 million USD by 2032. Historical movement between 2020 and 2025 shows moderate but consistent expansion, with revenue climbing from 597.5 million USD to 678.2 million USD over the period. This trajectory indicates a market where demand is anchored by regulatory requirements, operational safety mandates, and gradual capacity additions rather than volatile cyclical spikes.
When viewed across the historical window, the pattern underscores resilience. The 2020-2025 sequence moved through a brief contraction in 2021 before recovering through 2022 and 2023, then stabilizing near 646 million USD in 2024 before reaching the 2025 mark. The forecast horizon suggested a continued climb toward 722.27 million USD in 2026, 752.04 million USD in 2027, and 774.06 million USD in 2028, before a slight plateau near 773.96 million USD in 2029. Growth resumes afterwards, advancing to 796.12 million USD in 2030, 841.71 million USD in 2031, and 874.6 million USD in 2032. This shape implies that the segment will experience a transitional period around the late 2020s, likely shaped by order timing, replacement cycles, and the uneven rhythm of capital projects across regions.
Market concentration further clarifies the operating environment. The top three companies account for roughly 49.5% of revenue, while the top five reach about 65.2%. This distribution reflects a landscape where established manufacturers hold meaningful share through technical credibility, application-specific product lines, and long-standing customer relationships in process safety. At the same time, the space is not dominated by a single entity, leaving room for differentiation through specialization, service models, and regional execution.
Key Challenges and Inflection Points
The rupture disc market is entering a phase where growth is increasingly shaped by product suitability, qualification rigor, and the timing of end-use capital spending rather than by broad volume expansion alone. Several structural challenges stand out.
-
Qualification intensity and testing expectations are rising. Pressure relief components are increasingly expected to demonstrate traceable raw materials, lot-level qualification testing, and burst tolerance performance that exceeds baseline code requirements. Suppliers that cannot consistently document cycle life and performance consistency face greater friction in regulated and sanitary applications.
-
Demand timing is uneven across industries. While oil and gas, chemicals, and pharmaceuticals continue to anchor core demand, project pipelines differ by region and by budget cycle. Replacement activity can cushion downturns, but new installations often lag when capital expenditure decisions are delayed.
-
Segment differentiation is becoming a commercial necessity. The market spans metallic, graphite, and non-metallic rupture discs, each with distinct performance profiles for pressure relief, corrosion resistance, temperature exposure, and cleanability. Customers are selecting based on process conditions rather than commodity pricing, which pushes suppliers to align product design more closely with application-specific requirements.
These pressures create a market where success depends less on broad reach and more on technical fit, documentation reliability, and the ability to reduce installation or compliance friction for buyers.
Abrasive Disc Market
Core Drivers Shaping Market Direction
Technical Innovation and Application-Specific Engineering
Product development is increasingly oriented toward higher performance under demanding conditions and easier integration into complex systems. Recent moves to expand rupture disc families for larger sizes and high-performance overpressure protection show how manufacturers are targeting installations where pressure relief must be both reliable and scalable. Equally notable is the push toward assembly-based designs that simplify installation and improve process safety. Such products are not simply incremental variations; they reduce integration risk and support faster commissioning, which matters in environments where downtime is costly and safety validation is strict.
Innovation is also visible in how manufacturers are addressing material and performance requirements simultaneously. Metallic and graphite rupture discs are being positioned with emphasis on traceable sourcing and in-house lot qualification testing that surpasses standard code expectations for cycle life and burst tolerance. In high-compliance segments, this level of documentation is becoming part of the value proposition rather than a back-office requirement.
Regulatory and Standardization Pressure as a Demand Catalyst
Regulatory expectations and industry standards continue to reinforce demand for verified, repeatable pressure relief solutions. In pharmaceutical and biotechnology environments, sanitary rupture discs are expected to support traceability, cleanability, and sterilization, often aligned with recognized standards such as ASME BPE, USP Class VI, and 3A. In food and beverage processing, hygienic designs are expected to be compatible with cleaning-in-place and sterilization-in-place conditions while resisting vacuum exposure. These expectations push buyers toward products that can demonstrate compliance consistency across lots and operating conditions.
At the same time, certain materials are gaining traction because they align with specific process challenges. Graphite rupture discs, for example, are valued in some corrosive media applications due to temperature-independent material behavior and conformity expectations in regulated environments. This does not mean any single material dominates across all use cases; instead, it highlights that buyers are matching material properties to process environments more deliberately than in the past.
Demand-Side Shifts in Process Safety and Sanitary Applications
End-user demand is being shaped by a combination of operational safety priorities and the expanding requirements of hygienic processing. In chemical plants and oil and gas facilities, pressure relief remains a core function tied to equipment integrity and operational risk management. In pharmaceutical, biotechnology, and food-related applications, the emphasis shifts toward preventing contamination, enabling sterilization, and maintaining cleanliness without sacrificing overpressure protection.
This dual demand profile creates divergent purchase drivers. Process industries prioritize reliability, compatibility with harsh conditions, and long service life. Sanitary applications emphasize cleanability, compliance traceability, and compatibility with cleaning and sterilization routines. As a result, the same product category serves fundamentally different selection criteria depending on the end market, which diversifies the competitive battlefield.
Supply-Side and Cost Structure Considerations
Cost dynamics in this market are closely linked to material selection, manufacturing precision, and qualification overhead. Metallic rupture discs make up the largest portion of the revenue base, with graphite and non-metallic products forming substantial but smaller portions of the mix. This distribution matters because material choice affects not only performance but also sourcing complexity, testing requirements, and pricing strategy.
Suppliers that invest in raw material traceability and in-house testing may face higher operational burdens, but they also reduce the risk of qualification failures and customer rejections. Over time, this can translate into stronger repeat business in applications where documentation and consistency are decisive. Conversely, cost pressures may intensify where buyers treat rupture discs as interchangeable unless a supplier can clearly justify performance advantages or compliance benefits.
Competitive Positioning and Strategic Differentiation
The competitive landscape is defined by manufacturers that have built strong reputations around specific application strengths, product architectures, and compliance-oriented designs.
Some manufacturers have concentrated on sanitary and hygienic rupture disc solutions designed for pharmaceutical, biotech, food, and beverage environments. These offerings emphasize reverse-acting and forward-acting designs, compatibility with cleaning and sterilization processes, and adherence to recognized standards. The value proposition here is not simply pressure relief; it is repeatable cleanliness, sterilization readiness, and documentation that supports regulated operations.
Other manufacturers have broadened their footprint across chemical, pharmaceutical, extrusion, and food industries with both metallic and graphite products, often spanning reverse-acting, forward-acting, sanitary, and ultra-low or bi-directional applications. This type of positioning supports a strategy of cross-industry reach, where customers in multiple process environments can source from a single supplier with a wide performance envelope.
There are also manufacturers focused on engineered, high-precision rupture discs and pressure relief components for more demanding or specialized systems. In these cases, differentiation comes from precision manufacturing, custom engineering support, and the ability to integrate rupture discs into broader pressure relief solutions.
Geographically, the field also includes internationally based manufacturers serving industrial pressure relief applications with dedicated product series. These companies contribute to a market structure where regional execution, product line breadth, and technical support can be as important as headline brand recognition.
Recent Activity as a Window into Strategic Priorities
Recent product activity among leading manufacturers points to a clear strategic emphasis on performance range, installation efficiency, and line expansion. One notable direction has been the extension of established rupture disc lines into larger sizes to address higher-demand industrial applications. This suggests that manufacturers are responding to customers who need overpressure protection in more demanding configurations without abandoning proven design principles.
Another important move has been the launch of cartridge-based rupture disc assemblies intended to simplify installation and improve process safety. This reflects a broader shift toward reducing integration complexity, which is particularly valuable in facilities where maintenance access, replacement time, and installation accuracy directly affect operational continuity.
In parallel, the introduction of new rupture disc families for high-performance overpressure protection shows that suppliers are not relying on legacy portfolios alone. Instead, they are expanding into product sets designed to cover a wider performance spectrum, which can help capture demand from customers seeking a more consistent platform across multiple installations or process conditions.
Together, these developments indicate competition is increasingly being fought on the basis of application coverage, integration convenience, and validated performance rather than basic presence in the category.
Market Structure and Evolution Patterns
The current concentration pattern suggests a market that is consolidated enough to reward scale and technical credibility, yet open enough to allow differentiation by specialization. Companies with strong positions in sanitary or hygienic segments can outperform in regulated environments even if they are not the largest overall. Similarly, suppliers with broad material coverage and engineering support can build relevance across multiple industries by reducing the need for customers to manage several sources for different rupture disc types.
Looking ahead, the structure may evolve through a combination of selective consolidation and continued segmentation. Larger players may strengthen their position by broadening product lines or acquiring specialized capabilities, especially where compliance, testing, and documentation create high barriers to switching. At the same time, smaller or more specialized manufacturers can persist by serving niche performance requirements, regional demand, or application-specific customization that larger platforms do not prioritize.
For buyers, this environment often translates into a trade-off between simplified sourcing and best-fit performance. For suppliers, it means that competitive advantage is increasingly tied to how well a product platform aligns with customer qualification needs, installation constraints, and process conditions.
Future Outlook: Three Trends to Watch
Trend 1: Compliance and Documentation as Commercial Gateways
Over the next several years, traceability, qualification testing, and standards alignment are likely to become even more central to purchasing decisions, especially in pharmaceutical, biotech, food, and beverage applications. Buyers may increasingly treat documented consistency as a prerequisite rather than a bonus. This creates an opportunity for suppliers that already operate with rigorous raw material controls and lot-level testing, and a challenge for those that cannot match the same level of evidence when customers compare options.
The commercial implication is clear: in regulated segments, product performance and product documentation are becoming inseparable. Companies that can streamline qualification, reduce validation burden, and maintain consistent performance across lots are better positioned to secure long-term preference.
Trend 2: Platform-Based Product Strategies and Integration Convenience
A second trend is the move toward product families and assemblies that make selection, installation, and replacement more straightforward. Expanding line sizes and introducing cartridge-style designs are examples of how manufacturers are trying to reduce friction in the field. If this direction continues, buyers may value platform consistency across units and sites because it simplifies inventory planning, maintenance, and engineering review.
This trend opens commercial opportunities for suppliers that can offer a coherent range rather than isolated point products. It also raises the stakes for those whose portfolios are fragmented or difficult to standardize across applications.
Trend 3: Material Selection Becoming More Context-Specific
The market is unlikely to converge on a single material solution. Instead, metallic, graphite, and non-metallic rupture discs are expected to retain distinct roles based on pressure requirements, corrosion exposure, temperature conditions, and sanitary needs. The more important shift is that selection may become more deliberate, with buyers matching material characteristics to process environments rather than defaulting to a standard choice.
PW Consulting
This creates opportunity for manufacturers that can clearly articulate when and why a given material is appropriate, particularly in corrosive or temperature-sensitive services. It also suggests that sales and technical support will matter as much as the product itself, because the right choice often depends on operating conditions that differ from one installation to the next.
Risks and Uncertainties
Despite a generally constructive growth outlook, several uncertainties bear watching. Capital expenditure timing in oil and gas and chemical end markets can delay new installations and shift demand toward replacement cycles. Regulatory interpretations and customer qualification expectations can also evolve, changing the documentation or performance thresholds required for approval. Finally, raw material sourcing and manufacturing quality control remain sensitive points; any inconsistency in materials or testing can quickly affect customer confidence in safety-critical applications.
In addition, the late-2020s plateau visible in the forecast suggests that growth may not be linear. Periods of stabilization can emerge as project timing, replacement cycles, and regional demand patterns interact. Companies that rely too heavily on a single end-use sector or a narrow material set may feel those pauses more acutely than diversified competitors.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
-
Align product roadmaps with the applications where compliance documentation and performance consistency matter most. In sanitary and regulated environments, the ability to prove traceability and repeatable burst tolerance can be as influential as the headline design features.
-
Reduce installation and integration friction wherever possible. Cartridge assemblies, broader size ranges, and clearer platform consistency can make a product line easier to specify, deploy, and maintain, which strengthens customer preference over time.
-
Treat material strategy as application strategy. Rather than competing on a single material across all use cases, sharpen the message around where metallic, graphite, or non-metallic rupture discs are the best fit and support that claim with technical evidence.
For Investors and Strategic Planners
-
Focus on suppliers that combine application specialization with credible qualification practices. In a market where the top five companies hold a majority share, durable advantage often comes from segments where technical barriers and documentation requirements limit easy substitution.
-
Watch for platform expansion and consolidation signals. Product line broadening, assembly-based designs, and moves into larger-scale industrial protection can indicate where manufacturers are trying to capture more share per customer and reduce churn.
-
Consider how end-use timing affects revenue visibility. Because demand is influenced by project cycles in oil and gas, chemicals, and pharmaceuticals, diversification across applications and regions can reduce exposure to localized capital spending delays.
Rubber Diaphragm Market
For Procurement and Operations Leaders
-
Evaluate rupture disc suppliers on total qualification burden, not just unit price. In safety-critical or sanitary applications, consistency of documentation, testing evidence, and standards alignment can reduce risk and speed approval.
-
Standardize where possible, but preserve application fit. A coherent product platform across sites can simplify maintenance and inventory, but it should still be matched to pressure, temperature, corrosion, and cleanability requirements.
-
Request clear evidence of lot-level quality control and material traceability, especially where corrosive media, sterilization conditions, or stringent compliance expectations are involved. This helps ensure that the selected product performs consistently across installations.
Why Deeper Intelligence Matters Now
The rupture disc market is not undergoing a sudden disruption, but it is becoming more demanding in the ways that matter most to commercial decisions: qualification rigor, application fit, integration convenience, and documentation reliability. In that environment, general market awareness is useful, but segment-level clarity is what supports confident product planning, sourcing choices, and investment prioritization.
Detailed segmentation data, regional demand patterns, material and application splits, company-level positioning, and procurement-relevant benchmarks can sharpen these decisions considerably. For teams evaluating where to invest, which applications to prioritize, and how to compare suppliers beyond price, a more granular view of the market can help translate broad trends into actionable next steps. Readers seeking that level of detail can find it in the full PW Consulting report, which extends the analysis into deeper segmentation, competitive detail, and tailored decision frameworks.
For detailed analysis of this topic, please visit the official page: Rupture Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com